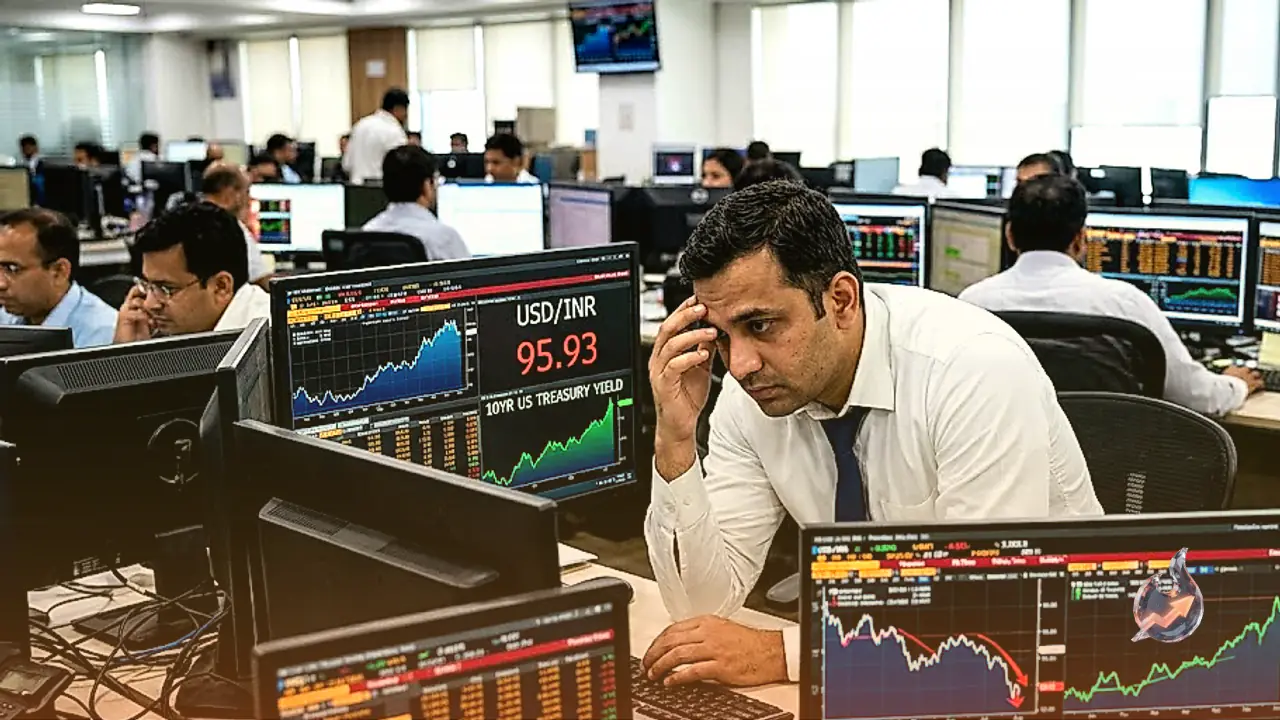















The Indian Rupee weakened against the US Dollar on Thursday, reversing previous session gains as an ongoing surge in United States sovereign debt yields fueled fresh demand for the greenback across global foreign exchange markets. The selling pressure on emerging market currencies steered the USD/INR currency pair higher toward 95.93. According to live market data, the exchange rate is trading around 95.99, slightly below the previous close of 96.05.
US Treasury Yields Touch Twenty-Year Peaks Near 5.31%
Global fixed-income markets witnessed significant movement as the benchmark 10-year US Treasury yield pushed toward 5.31%, marking its highest level in twenty years. This persistent upward trajectory in sovereign yields reflects expectations that borrowing costs in the world's largest economy will stay higher for longer. For international investors, a risk-free return exceeding 5% in US government debt substantially diminishes the risk-adjusted appeal of emerging market assets, triggering capital outflows from risk-sensitive currencies like the Indian Rupee into dollar-denominated debt securities.
Hawkish Fed Remarks and Kashkari's Rate Trajectory
Reinforcing the dollar's upward momentum, Federal Reserve Bank of Minneapolis President Neel Kashkari delivered decidedly hawkish commentary. The evaluation through the FXS Speechtracker scored his remarks at 7.1, notably above the historical average benchmark of 6.2. Kashkari underscored persistent worries that consumer price inflation hovering near 3% remains uncomfortably elevated. Furthermore, resilient economic expansion suggests that the current stance of monetary policy may not be exerting as much restriction as previously estimated.
Highlighting the likelihood of a higher neutral interest rate, Kashkari projected one additional rate hike during the current year, followed by another tightening move in 2027. This outlined path of prolonged policy restraint provides structural support for the US Dollar, even as policymakers express hope that measured tightening will eventually rein in inflation. Fed officials also harbor concerns regarding potential energy market disruptions. Geopolitical diplomacy between Washington and Tehran receded after President Donald Trump rejected reporting from Axios regarding possible sanctions relief for Iran, keeping oil supply risks elevated.
Private Payroll Additions and Shifting Rate Hike Timelines
Reinforcing the narrative of US economic resilience, the latest ADP Employment Change report established a robust foundation ahead of the official non-farm payrolls release. Private employers added 90,000 jobs, comfortably outperforming market consensus estimates of 70,000 and registering a sharp pickup from the 36,000 positions recorded in August. A tight labor market provides central bankers with greater latitude to maintain a restrictive policy posture.
In response to incoming economic prints, financial market participants adjusted their policy forecasts, pushing expectations for the Federal Reserve's next interest rate increase from October 28 back to December 9. Much of this reassessment stemmed from backward revisions within the Personal Consumption Expenditures price index published alongside August data. The government's annual benchmarking adjusted the July core PCE rate, which strips out volatile food and energy costs, downward from 3.3% to 3.0%.
USD/INR Technical Posture and Key Support Thresholds
From a chart perspective, USD/INR continues to trade with a mildly bullish bias around 95.9705, sustaining levels above its 20-day exponential moving average located at 95.7263. Maintaining this position above short-term trendlines signals underlying upward momentum, while the daily Relative Strength Index sits at 59.59. This reading indicates constructive price action without entering overbought territory, suggesting scope for further gains if critical support thresholds hold.
Live technical indicators confirm an established broader uptrend. The 14-day RSI stands at 55, while the MACD registers at 0.19 against a 0.15 signal line, displaying a positive histogram of 0.04. Moving averages show the 20-day EMA at 95.70, the 50-day EMA at 95.52, and the 200-day EMA down at 93.55, with the 50-day SMA at 95.48 and the 200-day SMA at 93.85. The 50-day EMA positioning above the 200-day EMA represents an active golden cross formation. Bollinger Bands (20, 2) span from 94.41 to 96.69 around a 95.55 midline, while the ADX reading of 33 points to solid trend strength. The Stochastic fast and signal lines stand at 89 and 90 respectively, with daily volatility measured by the 14-day ATR at 0.57. Pivot points identify central support-resistance at 95.93, with resistance levels at 96.04 (R1) and 96.10 (R2), and downside support marked at 95.87 (S1) and 95.76 (S2), within a broader 52-week band of 85.86 to 97.05.
Structural Drivers of the Rupee and RBI Market Dynamics
The Indian Rupee remains structurally vulnerable to global macroeconomic shocks. Because India relies on foreign producers for the vast majority of its crude oil requirements, international crude price spikes increase dollar outflows. Since international trade invoices are overwhelmingly settled in greenbacks, broad dollar strength directly translates into imported price pressures for domestic consumers. Capital flows, including Foreign Direct Investment and Foreign Institutional Investment, further dictate supply and demand balance for the local currency.
The Reserve Bank of India intervenes routinely in currency markets, absorbing or supplying dollars to mitigate excessive volatility and maintain orderly trading conditions. The central bank balances this market management against its primary domestic mandate of anchoring consumer price inflation around a 4% midpoint target through repo rate decisions. Elevated policy rates bolster the currency by facilitating the foreign exchange carry trade, where international institutional funds borrow at lower rates in developed economies to capture higher yielding sovereign and corporate debt instruments in India. While stronger domestic GDP growth draws capital and strengthens the exchange rate, elevated domestic inflation erodes purchasing power and widens the import bill, prompting central bank vigilance.
Performance of Major Global Currencies and Alternate Assets
Dollar resilience reverberated across international foreign exchange and commodity markets on Thursday. The Australian Dollar consolidated near two-month lows, hovering in the mid-0.6900 area during Asian trading hours. Even though moderated US PCE figures trimmed near-term Fed hike bets, energy-driven price pressures kept US debt yields firm. Australia's trade surplus narrowed sharply in August to 495 million Australian Dollars, exerting modest influence on AUD/USD trade.
The Japanese Yen hovered on the back foot as USD/JPY traded above 158.00 at the upper boundary of its weekly channel. Broad dollar demand outweighed speculation regarding Bank of Japan rate adjustments and the threat of official currency intervention from Tokyo authorities. Meanwhile, the EUR/USD pair languished near 1.1312, remaining around its lowest levels since May 2025 and substantially below its January peak of 1.2082, though upcoming Eurozone inflation data could provide a fresh catalyst.
In commodities, gold found modest technical buying interest near $4,139 per ounce following a pullback from earlier highs around $4,220, but multi-year highs in US Treasury yields capped upward momentum for the non-yielding metal. In the cryptocurrency sector, Hyperliquid (HYPE) dropped 2% on Thursday, retracing a portion of the previous day's 5% advance as institutional outflows of $5 million weighed on market sentiment, leaving token prices contained below the $90 threshold.