














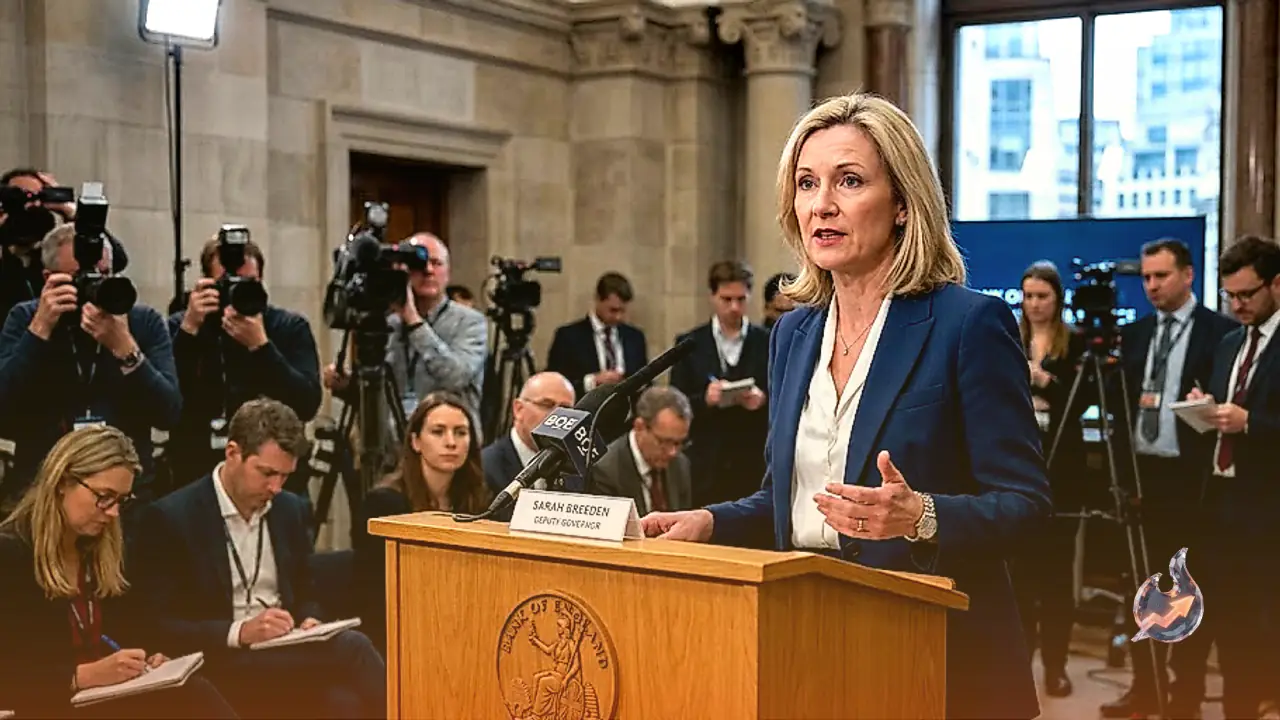

Mounting energy price volatility is testing the tolerance of central bankers in the United Kingdom, raising the prospect of tighter monetary conditions if upstream pressures persist. Sarah Breeden, Deputy Governor at the Bank of England, issued a clear warning on Thursday, stating that a downward trajectory for energy costs is anything but guaranteed. She cautioned that should the current energy disruption prove broader and longer-lasting, the case for a decisive central bank reaction will strengthen significantly. The shifting balance of economic risks means monetary authorities cannot afford to remain passive while inflationary dynamics take root.
Economic Slack and the Delay in Price Pass-Through
In her detailed assessment of market conditions, Breeden pointed out that the indirect transmission from escalating energy prices into wider consumer costs has remained relatively restrained so far. In macroeconomic terms, this indirect pass-through reflects how secondary goods and services absorb higher utility and fuel bills. The current muted spillover suggests the presence of underlying slack within the UK economy, where subdued demand and spare operating capacity temporarily discourage businesses from pushing wholesale cost increases directly onto consumers.
However, this absorption buffer has finite limits. Breeden warned that as an energy disruption expands in duration and intensity, businesses will inevitably reach the end of their margin flexibility. Once corporate margins are exhausted, companies will adjust their retail prices upward to survive, unleashing secondary inflationary waves across the domestic market. Emphasizing that waiting for definitive, undeniable proof of secondary effects could leave policy makers severely behind the curve, Breeden underscored that the central bank must stay ahead of corporate pricing behavior before inflationary expectations become deeply embedded.
Business Surveys and the Policy Mechanism in Focus
To gauge the pace at which firms are reacting to rising input expenses, Breeden stressed the critical importance of ground-level commercial intelligence. She noted that monitoring how enterprises approach their pricing decisions is central to her policy stance. Rather than relying solely on lagging official data, her evaluation draws heavily from forward-looking indicators, including the Decision Maker Panel survey, the Purchasing Managers Index, and intelligence gathered through the central bank regional agents network. These channels offer early visibility into whether businesses intend to pass elevated overheads directly onto end consumers.
As the institution charged with setting monetary conditions for the United Kingdom, the Bank of England operates with the primary statutory mandate of delivering price stability, defined as a headline inflation target of 2%. The central bank implements this mandate through its control over the base lending rate. By dictating the rate at which it lends to commercial banks and at which financial institutions lend funds to one another, the central bank directly dictates the overall price of borrowing across the wider financial system. Consequently, these rate determinations exert profound and immediate influence on the exchange rate of the British Pound.
How Interest Rate Cycles Shape the Pound
When domestic inflation overshoots the official 2% objective, the Bank of England responds by lifting interest rates, deliberately making consumer and commercial credit more expensive. This credit tightening reins in discretionary spending and slows business expansion, steadily draining excess demand from the economy to bring price growth back under control. Higher borrowing costs simultaneously create a strong tailwind for the British Pound, as international institutional capital flows toward the United Kingdom in search of superior yield on fixed-income assets.
Conversely, when inflation settles below the 2% threshold, it typically highlights softening domestic growth and sluggish economic turnover. Under those conditions, policy makers evaluate rate reductions to inject affordability into commercial credit, providing enterprises with cheap liquidity to fund productive, growth-generating investments. However, this accommodative easing cycle generally exerts downward pressure on the British Pound, as compressed domestic yields encourage international money managers to seek higher returns in competing foreign jurisdictions.
Balance Sheet Interventions Through QE and QT
During severe financial panics and prolonged liquidity logjams where traditional rate reductions reach their practical floor, the Bank of England can deploy Quantitative Easing as a last-resort intervention. Under this stimulus framework, the central bank creates new reserves to purchase substantial volumes of sovereign bonds and top-tier AAA corporate securities directly from commercial lenders and non-bank financial institutions. By swapping illiquid paper for readily available central bank reserves, the policy injects immediate liquidity into paralyzed credit channels. Because it expands the domestic money supply dramatically, Quantitative Easing historically correlates with a weaker British Pound.
Quantitative Tightening operates as the precise counterbalance to bond purchases, utilized when the real economy strengthens and inflation pressures mount. While Quantitative Easing involves expanding the central bank balance sheet to stimulate borrowing, Quantitative Tightening mandates that the Bank of England halt fresh bond purchases altogether. Furthermore, the central bank ceases reinvesting the principal proceeds received when existing bond holdings mature. This systematic balance sheet reduction drains excess liquidity from the financial system and typically provides sustained structural support to the value of the Pound.
Global Currency and Bond Market Realignments
The policy deliberations in London arrived amid notable shifts across global financial hubs. In Asia, the Australian Dollar pulled back toward the 0.7000 threshold against the US Dollar during Thursday trade following the release of Australia August employment figures. The data revealed that the nationwide unemployment rate climbed to 4.6%, exceeding the market projection of 4.5%. Despite the higher jobless rate, the headline employment change showed resilient workforce additions of 39.5 thousand, comfortably beating expectations. Concurrently, market participants exhibited clear caution ahead of high-stakes diplomatic talks between US President Donald Trump and Chinese President Xi Jinping.
Meanwhile, the Japanese Yen rallied against the US Dollar, dragging the currency pair away from three-week highs toward the 158.00 zone during Asian trading hours. A sharp run-up in domestic Japanese sovereign bond yields underpinned the Yen amid persistent market chatter regarding potential official currency interventions. At the same time, the broader US Dollar Index maintained its footing near two-month peaks, sustained by firm US Treasury yields and market expectations of a prolonged restrictive monetary posture by the Federal Reserve.
Gold Softens as Global Central Banks Adjust Levers
Precious metals experienced modest headwinds, with spot gold extending its decline for a second consecutive session below the $4,300 mark to test one-week lows during the early European morning. Investors remained hesitant to build fresh positions in bullion ahead of the bilateral summit between Donald Trump and Xi Jinping. Although baseline expectations for major diplomatic breakthroughs remain subdued, commodities traders are closely monitoring potential developments surrounding rare earth export quotas, semiconductor export restrictions, and the preservation of the existing bilateral trade ceasefire.
In continental Europe, the Swiss National Bank chose to keep its key policy rate stable at 0%, matching the broad consensus among global analysts. In its accompanying monetary policy assessment, the Swiss central bank specified that commercial banks sight deposits will receive interest at the baseline policy rate up to a predefined limit. Looking further out, the institution lifted its 2026 inflation forecast to 0.7% from a previous projection of 0.6%, noting that structural risks facing the Swiss domestic outlook originate primarily from volatility across the global macro environment. In East Asia, the Bank of Japan advanced its policy normalisation cycle by raising its short-term policy interest rate target from 1.00% to 1.25% through a 7-2 majority vote, bringing an end to weeks of persistent market speculation.