














Major foreign exchange and commodity markets traded with noticeable volatility on Friday as the British Pound attempted to stabilize just above the prior session low of 1.3336. Fresh macroeconomic data showed an unexpected improvement in consumer activity across the United Kingdom, reversing the downward momentum recorded in July. However, broader monetary considerations surrounding the Bank of England continue to create headwinds for sterling against the US Dollar.
UK Retail Volumes Post Surprise Upturn in August
Consumer spending figures in the UK delivered an upside surprise in August, defying broader expectations of persistent weakness. Total retail sales volumes increased by 0.5% month over month, sharply outperforming the consensus projection of a 0.2% decline. In July, total retail volumes had contracted by 0.5%.
A similar trajectory was visible in the core metric that excludes automotive fuel. Core retail sales rose by 0.6% on a monthly basis, beating market forecasts that pointed to a 0.2% drop, and turning around from a steep 0.9% fall recorded in July. The figures indicate that underlying retail demand held up better than projected through the late summer period.
Bank of England Rate Trajectory and Sterling Vulnerabilities
Financial market pricing reflected in the interest-rate swaps curve continues to imply roughly 100 basis points of policy tightening by the Bank of England over the coming twelve months, which would take the benchmark rate to 4.75%. Despite those expectations, broader economic conditions suggest the central bank may not need to implement policy tightening to the extent that money markets anticipate.
The British economy is currently operating below its potential productive capacity. With the Bank Rate positioned at 3.75%, monetary settings are already hovering near the upper end of the Bank of England's neutral interest rate range, estimated between 2% and 4%. Furthermore, domestic fiscal policy is anticipated to turn increasingly restrictive. Given these underlying factors, sterling remains sensitive to any dovish shift in expectations should investors adjust their projections for central bank policy lower.
Australian Dollar Gains Support Before Hitting US Dollar Ceiling
In other currency pairings, the Australian Dollar maintained a constructive tone for a second consecutive trading session, holding above 0.7100 during Friday's Asian session. A pullback in US bond yields helped temper demand for the greenback, offering immediate support to the pair.
Reserve Bank of Australia Governor Bullock provided additional momentum through hawkish remarks that fueled speculation of further policy tightening. Nevertheless, the pair faced clear upside resistance as broader dollar weakness remained contained by the Federal Reserve's restrictive stance and ongoing geopolitical tensions, preventing more pronounced gains in AUD/USD.
Bank of Japan Rate Hike to 1.25% Overshadowed by Board Dissents
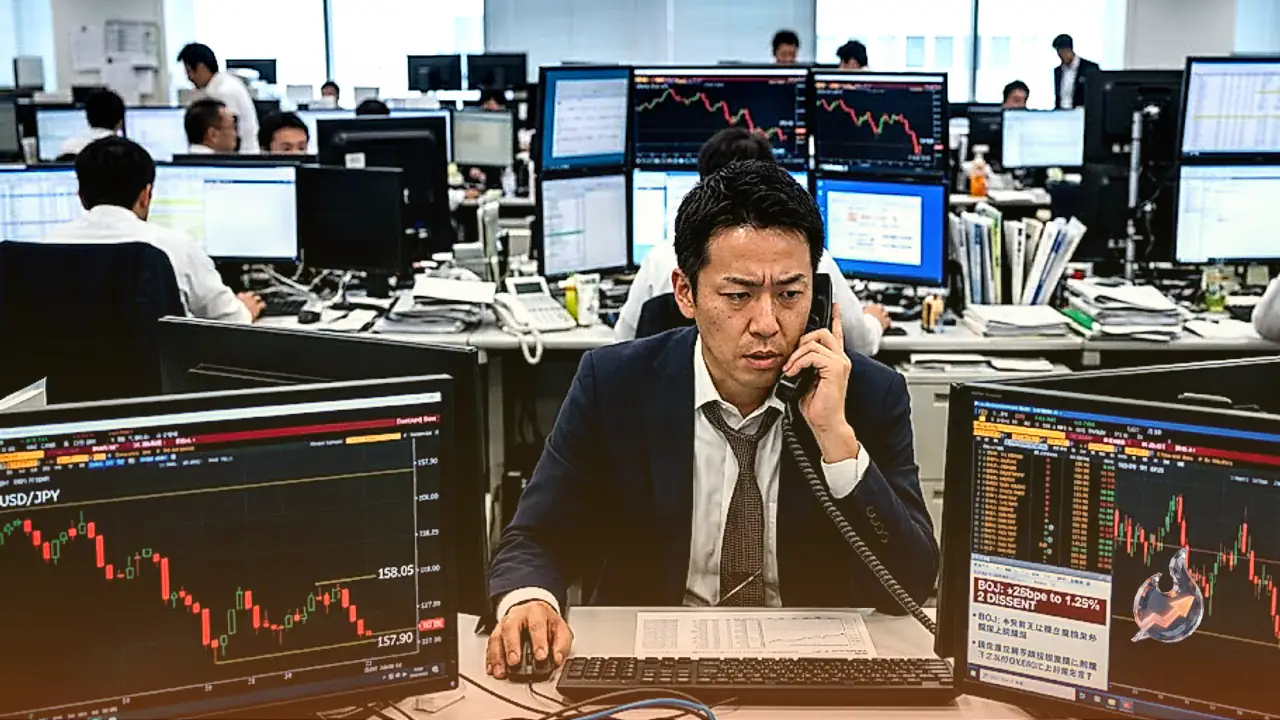
Moving into the European session, USD/JPY advanced toward 158.00, touching a fresh two-week high. The Japanese Yen continued to weaken even after the Bank of Japan decided to raise its short-term interest rate target from 1.00% to 1.25%.
The policy decision passed by a 7-2 vote, marking another formal step in Japan's monetary policy normalization and matching widespread expectations built up over preceding weeks. Following the announcement, Governor Kazuo Ueda stated that the policy phase had changed. Even so, the presence of two surprise dissenting votes against the rate hike created market skepticism, offsetting Governor Ueda's hawkish tone and leaving the yen vulnerable to sustained selling pressure.
Gold Rallies Near $4,370 Supported by Softening Crude Oil
In precious metals, gold maintained its constructive momentum into Friday, changing hands with solid gains around the $4,370 per troy ounce region. The yellow metal drew support from declining international crude oil prices, which helped bullion withstand pressure from a firm US Dollar and rising US Treasury yields across various maturities.