














Trading dynamics across international foreign exchange markets have placed the Euro under sustained selling pressure, steering the single currency toward a weekly loss against the US Dollar. Persistent expectations of prolonged monetary tightening by the Federal Reserve have continued to reinforce demand for the Greenback. At the same time, ongoing supply worries stemming from the Middle East have prevented a significant slide in crude oil prices, maintaining upward pressure on global inflation projections. Addressing the macroeconomic landscape, European Central Bank President Christine Lagarde affirmed that the Frankfurt-based central bank remains well positioned to address inflation risks generated by energy market volatility.
Crude Oil Fluctuations Drive US Treasury Yields Higher
Downside momentum in energy benchmarks has remained constrained as Middle Eastern supply vulnerabilities continue to overshadow market sentiment. West Texas Intermediate crude is hovering around $97.20, staging an intraday recovery after slipping to a session low of $94.63. This rebound in oil prices has reignited upward pressure on sovereign debt yields across the board. The benchmark US 10-year Treasury yield is currently hovering near 4.98%, approaching the multi-year peak of 5.04% touched on Tuesday, which marked its highest mark since 2007. The prospect of borrowing costs remaining higher for an extended duration has continued to underpin broader financial conditions.
Dollar Index Touches Multi-Week Peak Amid Rate Hike Bets
The lingering possibility of further policy tightening in the United States has kept capital flowing steadily into the US Dollar. The US Dollar Index, which gauges the performance of the American currency against a basket of six principal trading peers, has advanced past 100.50, registering its strongest valuation in seven weeks. Market pricing continues to reflect shifting expectations for the Federal Reserve's upcoming schedule. According to metrics compiled by the CME FedWatch Tool, financial market participants currently price in approximately a 55% probability that the Fed will implement another 25-basis-point interest rate increase in October. Investor attention is now shifting toward a dense lineup of scheduled appearances by central bank officials next week, which traders will scrutinize for definitive policy signals.
Nordea Economists Weigh In on Central Bank Trajectories
Market projections regarding the path of European monetary policy have outpaced previous economic assumptions. Analysts at Nordea have highlighted that pricing across financial markets has expanded rapidly in recent sessions, climbing substantially beyond their original baseline projection. That prior baseline had envisioned two additional 25-basis-point rate hikes from the European Central Bank, spaced out with one occurring in December and the subsequent adjustment arriving in March 2027. Nordea strategists emphasize that soaring energy costs have served as the primary catalyst behind heightened rate hike expectations, especially as profound uncertainty surrounding Middle Eastern developments continues to complicate the regional economic outlook.
Monetary Mechanics of the European Central Bank
Headquartered in Frankfurt, Germany, the European Central Bank operates as the monetary authority for the member states of the Eurozone. The central bank holds responsibility for determining benchmark interest rates and steering macroeconomic policy across the monetary union. Its primary constitutional mandate is the preservation of price stability, defined as sustaining headline inflation at or near the 2% target over the medium term. The governing institution's primary mechanism for achieving this target is the upward or downward adjustment of policy rates. In typical market environments, maintaining higher interest rates enhances capital attractiveness and yields a firmer Euro, whereas policy easing tends to soften the currency.
Monetary decisions are made by the ECB Governing Council during eight regularly scheduled policy meetings each year. These decisions are formulated through deliberations between the governors of Eurozone national central banks and six executive board members, led by ECB President Christine Lagarde. Outside standard interest rate levers, the institution retains unconventional policy mechanisms to deploy during severe financial crises.
Contrasting Quantitative Easing and Quantitative Tightening
Under exceptional economic strain, the European Central Bank can activate Quantitative Easing. This mechanism involves the creation of new central bank reserves to purchase financial assets, primarily sovereign debt and corporate bonds, directly from institutional balance sheets. The injection of liquidity via this process generally depresses the valuation of the Euro. It functions as an extraordinary measure when conventional rate reductions no longer suffice to guarantee price stability. Historical deployments of this tool occurred during the sovereign debt and financial crises between 2009 and 2011, throughout the low-inflation environment of 2015, and amid the market disruptions triggered by the pandemic.
Conversely, Quantitative Tightening represents the unwinding phase once economic expansion is established and inflationary trends gather pace. Rather than accumulating assets to distribute liquidity, the central bank ceases net bond purchases and terminates the reinvestment of maturing debt principal. This balance sheet contraction removes excess liquidity from circulation, an action that generally offers structural support and a bullish tailwind for the Euro.
Movements in the Australian Dollar and Japanese Yen
Cross-currency flows across other major pairs showed distinct trends. The Australian Dollar maintained positive trading traction for a second consecutive session, holding firmly above 0.7100 during Friday's Asian trading window as softer US bond yields provided relief against greenback strength. Furthermore, hawkish commentary from Reserve Bank of Australia Governor Bullock provided additional momentum to domestic rate hike expectations, offering solid support to the Aussie. Nonetheless, the prevailing hawkish posture of the Fed and persistent geopolitical uncertainties capped the advance.
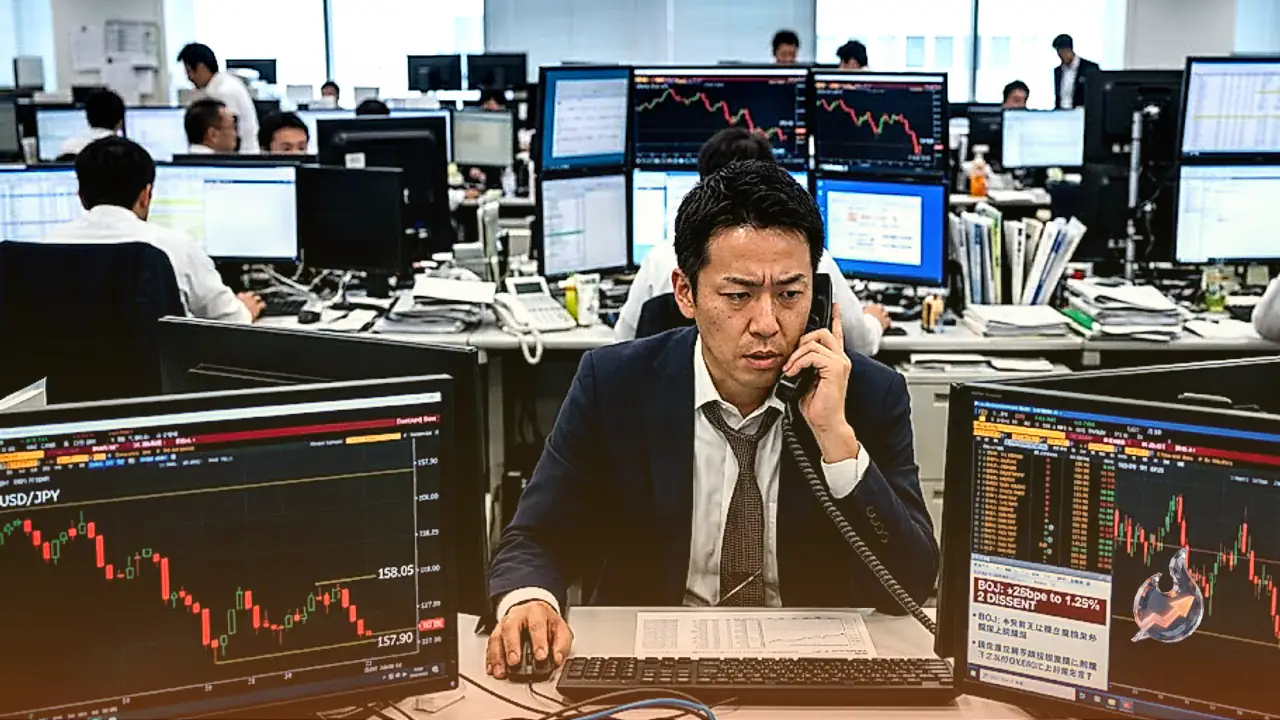
In contrast, the Japanese Yen resumed its downward slide during Friday's European trading hours, driving USD/JPY toward the 158.00 threshold and touching fresh two-week highs. The Yen weakened despite an anticipated rate hike from the Bank of Japan, which raised its short-term interest rate target from 1.00% to 1.25% following a 7-2 committee vote. While the move marked another deliberate step toward normalising monetary policy and matched broad market consensus, the emergence of two surprise dissenting votes against the hike, combined with hawkish remarks from Governor Ueda, left the Yen vulnerable to persistent selling pressure.
Precious Metals Advance as Bitcoin Consolidates Gains
The commodities complex saw spot gold extend gains accumulated during the second half of the trading week, changing hands near $4,370 per troy ounce on Friday. Bullion found support from transient softening in crude prices earlier in the week, allowing buyers to absorb the headwinds generated by an ascending US Dollar and elevated Treasury yields across maturities.
Meanwhile, the digital asset sector saw Bitcoin stabilize following a significant summer rebound. After dropping to a yearly low of $57,800 in July, Bitcoin staged an impressive advance of nearly 33%, securing consecutive monthly gains throughout July and August. Despite this pronounced rally, the cryptocurrency trades roughly 40% below its historical peak. Market participants remain divided over whether this price action signals the onset of a new macro bull run or represents a corrective recovery within an overarching bear-market structure.