













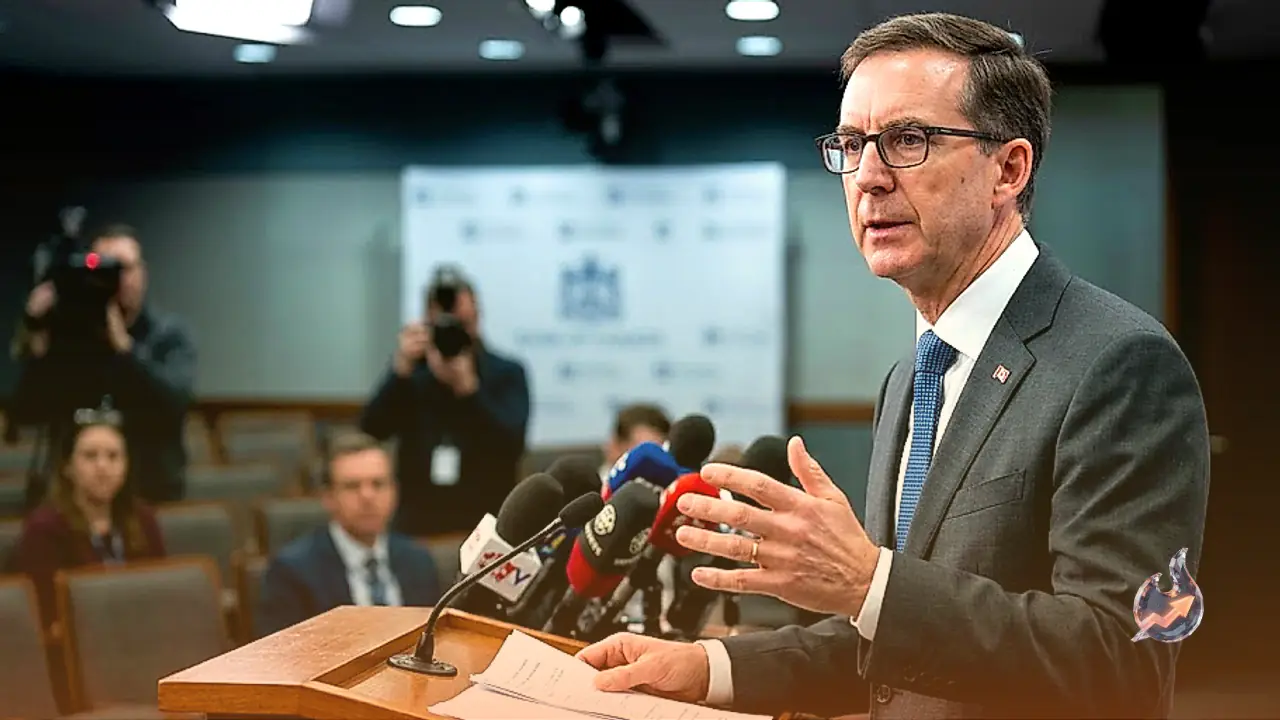

Monetary policy trajectories across leading global economies are undergoing notable shifts as central bankers contend with persistent inflation pressures and currency volatility. At the forefront, expectations surrounding the Bank of Canada have begun tilting toward earlier interest rate hikes. Bank of Canada Governor Tiff Macklem is scheduled to deliver a speech on economic developments this Monday in Halifax, an appearance widely anticipated to offer fresh guidance prior to the governing council's scheduled rate announcement on Oct. 28.
Energy Costs and Inflation Passthrough Dynamics
During its most recent policy gathering, the Bank of Canada formally flagged heightened concerns regarding the broader inflationary consequences stemming from elevated energy prices. Nonetheless, the detailed meeting minutes clarified that policymakers are predominantly attentive to the passthrough of energy costs into general price indices rather than the elevated oil prices in isolation, a variable the central bank cannot directly influence. Because underlying inflationary pressures could become entrenched through these secondary channels, the balance of risks surrounding the current monetary forecast is actively shifting toward earlier rate increases.
Bank of Japan Delivers Expected Rate Increase
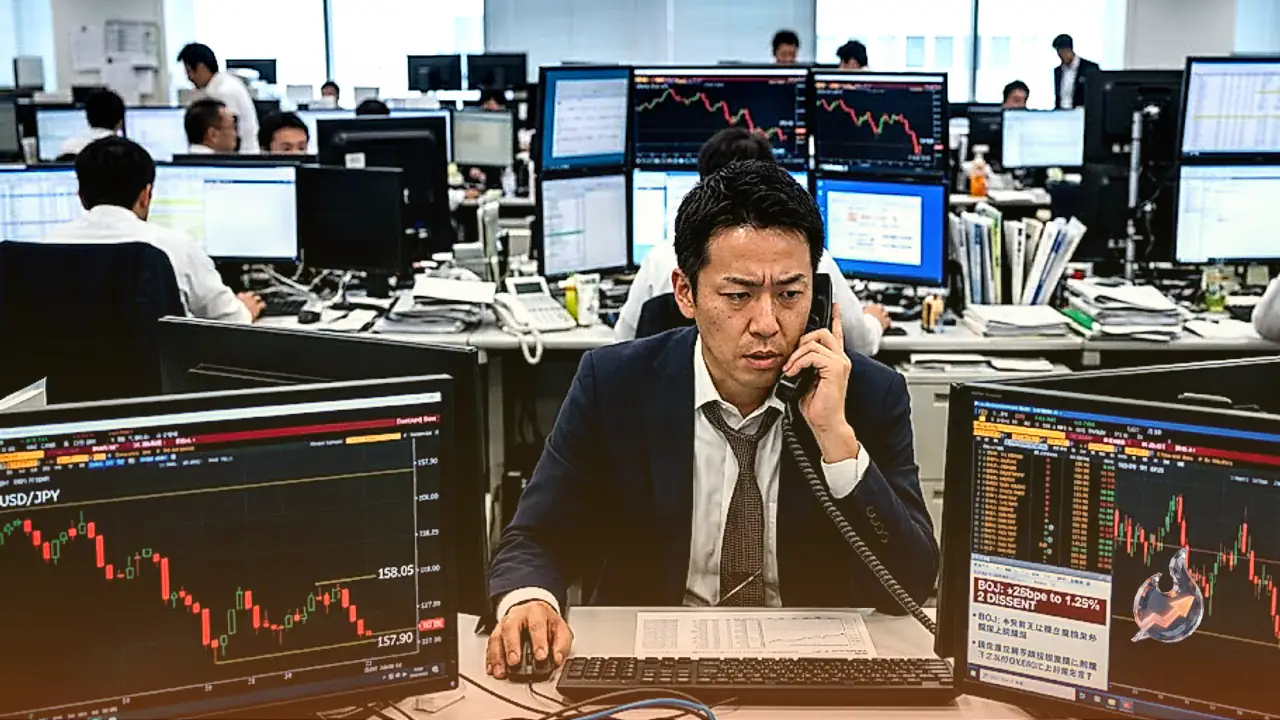
In Asia, the Bank of Japan advanced its monetary policy normalisation by lifting its short-term interest-rate target from 1.00% to 1.25%. The decision was secured through a 7-2 vote, matching the consensus expectations that market participants had priced in over preceding weeks. Following the decision, Governor Kazuo Ueda observed that the policy phase had fundamentally changed, signaling a departure from prior ultra-loose settings.
Despite the rate hike to 1.25% and the hawkish tenor of Governor Ueda's remarks, the Japanese Yen faced renewed selling pressure. During Friday's European trading hours, USD/JPY extended its upward momentum, refreshing two-week highs as it approached the 158.00 threshold. The presence of two unexpected dissenting votes against the rate hike weighed visibly on the Yen, blunting the immediate supportive impact of the tightening action.
Currency Pair Dynamics and Precious Metal Strength
In other currency segments, AUD/USD displayed a positive bias for the second consecutive session, maintaining its footing above the 0.7100 mark during Friday's Asian trading window. A softer tone in US bond yields kept buyers of the US Dollar cautious. At the same time, hawkish commentary from Reserve Bank of Australia Governor Michele Bullock bolstered market expectations of domestic policy tightening, lending direct support to the Australian currency. However, the broader hawkish stance maintained by the Federal Reserve, coupled with ongoing geopolitical uncertainties, curbed losses for the greenback and placed an upper cap on the pair's gains.
Meanwhile, bullion markets built upon the optimism established during the latter half of the trading week. Gold traded with notable gains near the $4,370 region per troy ounce on Friday. The precious metal gathered sustained upward momentum from retreating crude oil prices, which effectively counterbalanced the concurrent rise in the US Dollar and climbing yields across the US Treasury curve.