














Monetary tightening across the euro area appears to be nearing its conclusion as financial institutions reassess the trajectory of consumer prices. Rabobank strategists Bas van Geffen and Elwin de Groot anticipate that the European Central Bank will implement a 25 basis point increase to its key deposit facility rate during its upcoming policy gathering in December. Such a move would raise the benchmark rate to 2.75%, driven by updated energy price projections that present immediate upside risks to headline inflation.
Energy Cost Projections and the Inflationary Impulse
The anticipated adjustment is not viewed by analysts as a fundamental shift toward an accelerated or prolonged phase of policy tightening. Instead, the move represents a calculated response to fresh pressures across energy markets. Strategists Bas van Geffen and Elwin de Groot noted that the incoming energy shock exerts a swifter and more pronounced upward pull on inflation measures than on broader real economic output. Under these conditions, a calibrated rate hike is considered necessary to keep medium-term inflation expectations anchored and prevent widespread secondary price pressures from embedding themselves in the regional economy.
The extended presence of elevated energy prices poses a tangible threat of secondary effects spilling into non-energy goods, corporate pricing power, and wage negotiations. As long as high energy costs linger, the risk of these broad-based spillover effects increases substantially. However, the strategists pointed out that the two prior policy rate increases, coupled with the prospective December hike, are specifically calibrated to mitigate that exposure. Provided that upcoming macroeconomic indicators and business surveys do not show evidence of secondary inflationary effects taking hold, policymakers will not be required to respond with more forceful interventions.
Projected Policy Pause as Pressures Abate by March
Financial strategists emphasize that any additional policy tightening delivered before year-end will likely be transitory. Projections suggest that wholesale energy price pressures will begin to diminish starting in March. Once this relief materializes across commodity channels, the rationale for keeping benchmark rates at continually higher levels will weaken significantly. Strategists believe that once the immediate energy impulse begins to clear, central bankers will no longer face compelling pressure to sustain an overt tightening bias.
Consequently, the baseline expectation calls for only one additional rate adjustment in December, after which the tightening cycle is anticipated to pause. While an broadening of price pressures beyond energy could reintroduce upside risks to borrowing costs, current market fundamentals point toward a near-term ceiling in official interest rates.
Cross-Asset Movements and Divergent Global Central Bank Action
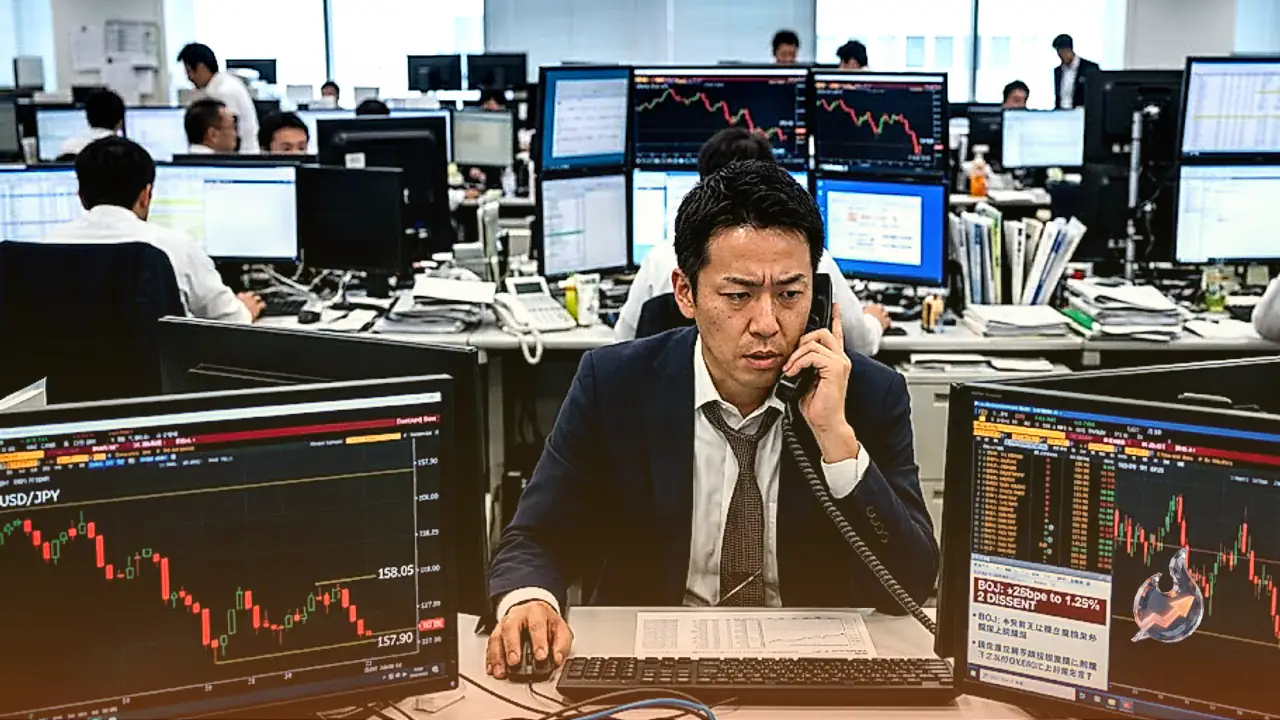
Developments surrounding European monetary policy are unfolding against a broader backdrop of divergence across international financial markets. In Asia, the Bank of Japan moved further along its path toward policy normalization by lifting its short-term interest rate target from 1.00% to 1.25%. The rate decision passed via a 7-2 majority vote, closely aligning with consensus expectations that had formed over several weeks. Despite the move and accompanying policy remarks from Governor Ueda, the Japanese Yen lost ground as two unexpected dissenting votes inside the policy board unsettled currency traders. As a result, USD/JPY advanced toward the 158.00 threshold during Friday's European trading hours, marking fresh two-week highs.
In foreign exchange markets elsewhere, the Australian Dollar maintained a positive footing for a second consecutive session. During Asian trading on Friday, AUD/USD held firm above the 0.7100 handle, buoyed by softer United States Treasury bond yields and supportive policy remarks from Reserve Bank of Australia Governor Bullock regarding interest rate hike possibilities. Simultaneously, lingering geopolitical tensions and expectations surrounding the Federal Reserve's policy horizon helped contain broader losses for the United States Dollar, placing a ceiling on the currency pair's upward momentum.
Commodities and alternative assets reflected similar shifts in yield dynamics. Spot gold advanced for a second straight session to reach new weekly highs during the first half of Friday's European trading window, with market participants closely monitoring price action around the $4,400 mark amid retreating sovereign yields. In the digital asset sector, Bitcoin recorded a notable rebound from its annual low of $57,800 seen in July. Supported by consecutive monthly gains across July and August, the cryptocurrency climbed by nearly 33%, though it remains positioned roughly 40% beneath its historical all-time peak.