













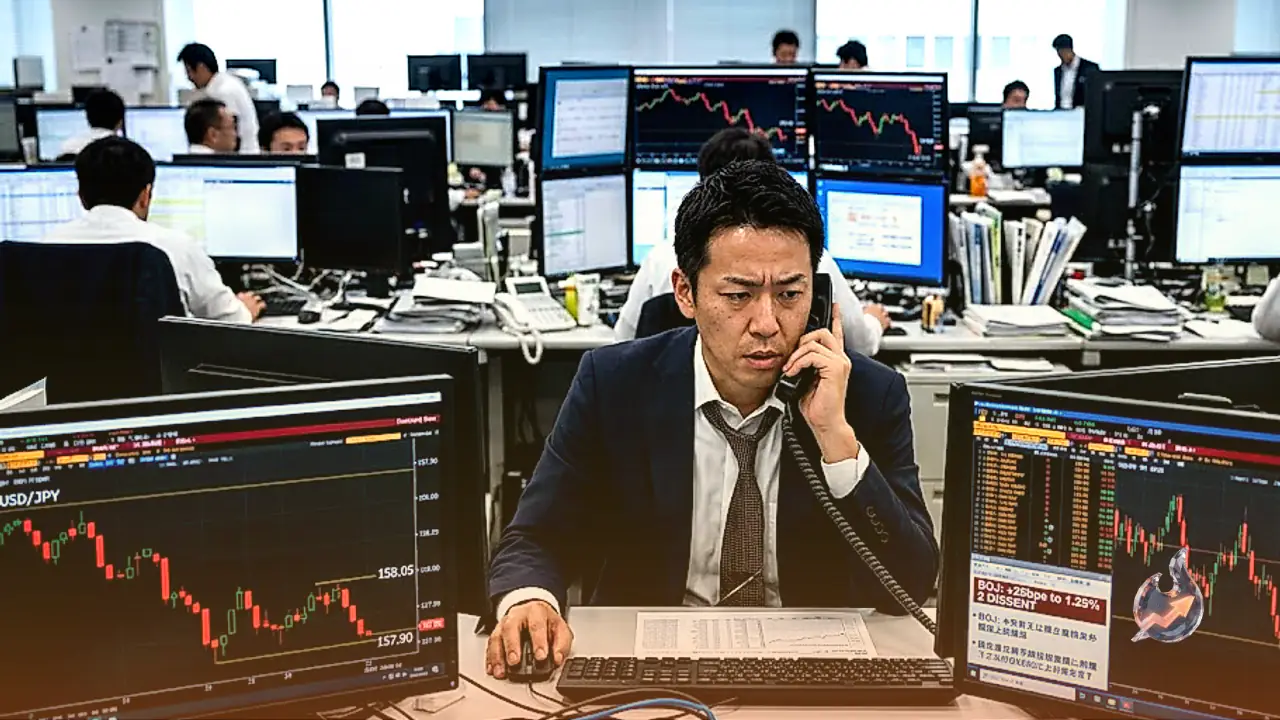

A widely predicted monetary tightening move by the Bank of Japan failed to provide support to the Japanese Yen in global currency markets on Friday. The central bank lifted its short-term interest-rate target by 25 basis points to 1.25% from 1.00%, carrying forward its broader push toward the normalisation of monetary policy after weeks of market expectations that had already fully priced in the change. Instead of appreciating, the Japanese currency weakened sharply against the greenback, driving USD/JPY to around 157 during morning trading before building additional momentum into the European session to reach a two-week peak near 158.00.
Internal Divide and a 7-2 Policy Vote
Market attention quickly gravitated beyond the headline rate adjustment to the internal division revealed within the monetary policy committee. The rate decision passed with a 7-2 majority, as board members Toichiro Asada and Ayano Sato voted against the 25 basis point hike. Both dissenting officials were appointed to the board by Prime Minister Takaichi, a political background that traders interpreted as an indirect reflection of the government's cautious stance regarding tighter credit conditions. Even with hawkish rhetoric from Governor Ueda alongside the policy announcement, the two surprise dissents raised doubts over how aggressively the central bank can continue raising borrowing costs going forward.
Cooling Inflation and Subdued Domestic Price Pressures
Underlying macroeconomic indicators published ahead of the policy verdict offered additional justification for market skepticism regarding further rate increases. Japan's August core consumer price index, which excludes fresh food prices, edged lower to 1.7%, sliding below the consensus expectation among economists. With domestic price pressures remaining decidedly modest, investors viewed the combination of weakening underlying inflation and visible internal policy friction as a clear sign that the Bank of Japan faces meaningful structural hurdles in sustaining its tightening momentum.
Australian Dollar Gains Traction Amid Global Moves
Currency trading elsewhere across the Asian session showed divergence, with AUD/USD trading with a positive bias for a second straight day and maintaining ground above 0.7100. Lower US Treasury bond yields kept Dollar bulls restrained, while hawkish comments delivered by Reserve Bank of Australia Governor Bullock fueled expectations of higher domestic interest rates and offered solid backing to the Australian Dollar. Nevertheless, ongoing geopolitical uncertainties combined with the Federal Reserve's own hawkish stance prevented extended losses for the US Dollar, ultimately placing a cap on the pair's upward trajectory.
Gold Strengthens as Crude Oil Drops
In commodities, gold sustained the positive tone established during the latter half of the week, changing hands with solid gains around the $4,370 region per troy ounce on Friday. The upward movement in the precious metal drew significant momentum from falling crude oil prices. This weakness in energy commodities provided sufficient support to counterbalance both the broader advance of the US Dollar and climbing US Treasury yields across the entire curve, preserving gold's safe-haven appeal among global market participants.
Bitcoin Rebound Faces Critical Long-Term Test
The cryptocurrency market also mirrored shifts in broader risk sentiment as Bitcoin continued to build on its mid-year recovery. After slumping to a yearly low of $57,800 in July, BTC recorded consecutive monthly advances across July and August, generating an overall rebound of nearly 33%. Despite that substantial recovery, the token continues to trade roughly 40% beneath its record high. This lingering valuation gap leaves market participants actively debating whether the recent upward momentum marks the opening phase of a genuine bull run or represents a secondary relief rally inside an ongoing bear-market trend.