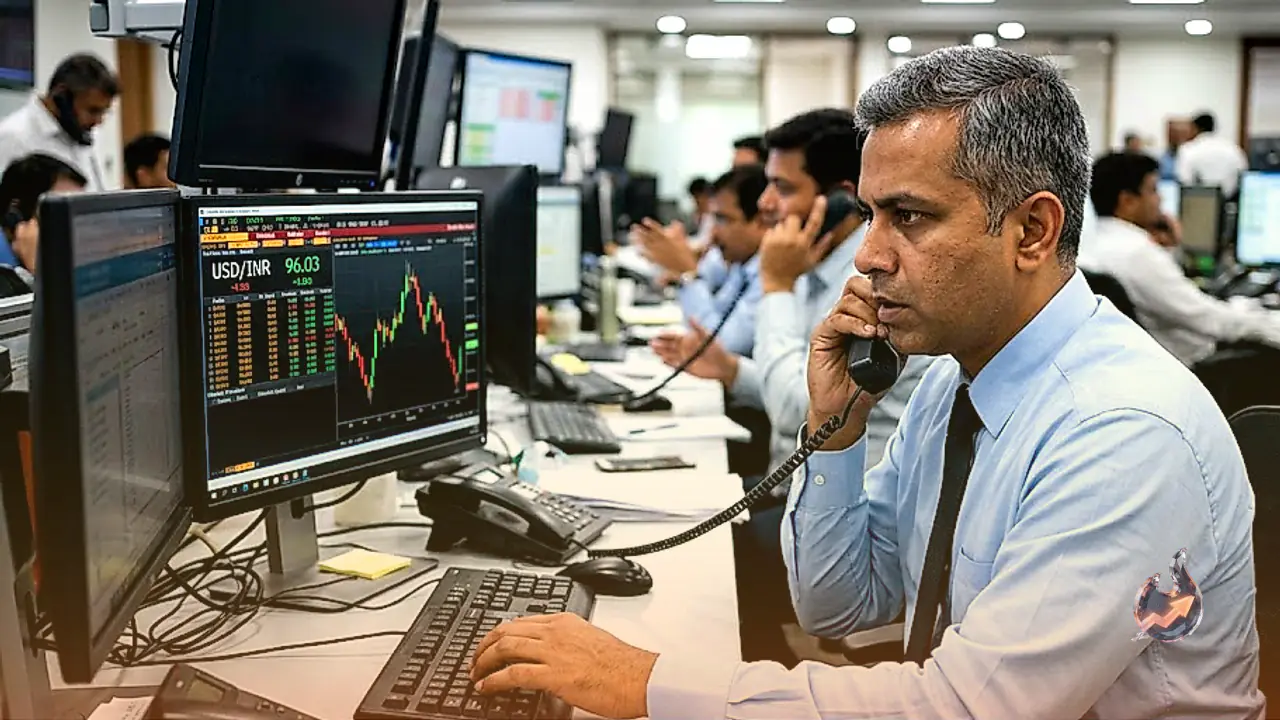














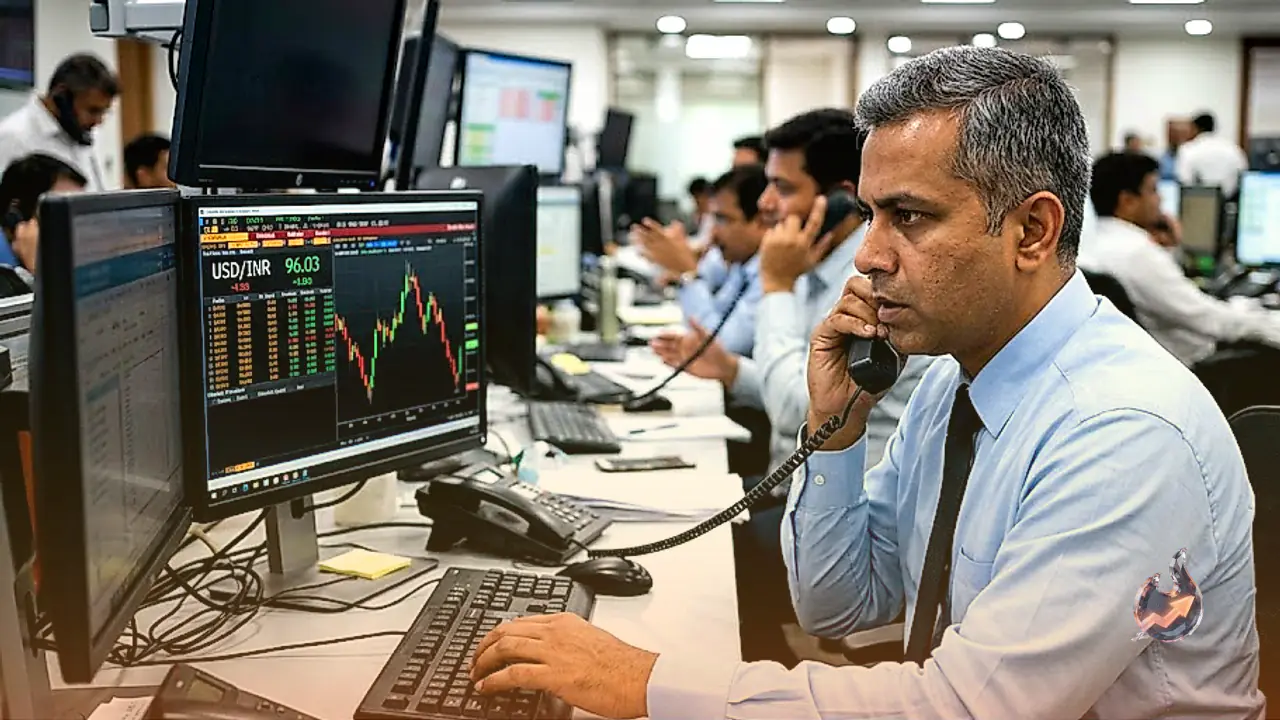

The Indian Rupee managed to halt its downward slide against the US Dollar on Friday, securing a temporary foothold around the critical 96.00 threshold after enduring persistent selling pressure in recent sessions. The USD/INR currency pair encountered stiff resistance in extending gains beyond 95.96, largely restrained by suspected intervention from India's central bank. Market participants noted that the monetary authority stepped in to offload US Dollars prior to the official opening of the local spot market, a strategic maneuver that successfully prevented the domestic currency from tumbling past the pivotal 96 per dollar barrier. According to live market data, USD/INR is trading around 95.85, up 0.11 percent from the previous close of 95.74, with a 52-week trading span ranging from 85.86 to 97.05.
Surging Treasury Yields and Energy Market Volatility
Despite the momentary stabilization, currency strategists warn that the Rupee's recovery remains fragile against a backdrop of surging United States Treasury yields and elevated energy markets. Expectations that the Federal Reserve will maintain interest rates at restrictive levels for a prolonged period continue to lend robust fundamental backing to the greenback. In early domestic trade, the MCX Crude Oil contract set to expire on October 19 pulled back by 2.3 percent to hover near Rs. 8,950, though this dip followed sharp rallies across the preceding two sessions. Meanwhile, the benchmark 10-year US Treasury yield hovered near 5.23 percent, lingering close to its 19-year peak established on Thursday.
A broader surge in energy costs, with crude prices rebounding above the $100 per barrel mark, alongside multi-year highs in US Purchasing Managers Index metrics and uncompromising rhetoric from Federal Open Market Committee officials regarding future policy paths, has driven yields higher across the entire Treasury curve. Because Treasury Notes represent roughly 52 percent of all marketable US debt instruments, escalating yield trajectories pose significant challenges to the sovereign fiscal outlook.
Federal Reserve Outlook Tightens Pressure on Asian Currencies
Assessing the global macroeconomic landscape, analysts at MUFG observed that financial markets are pricing in roughly 37 basis points of incremental policy tightening by the Federal Reserve through December 2026, which translates to approximately 1.5 rate increases before year-end. The financial institution warned that ongoing economic resilience increases the likelihood of monetary authorities implementing further restrictive measures to prevent inflationary pressures from becoming structurally entrenched. This hawkish policy trajectory continues to generate significant headwinds for broader risk-sensitive assets, placing Asian currencies in an exceptionally demanding environment.
Domestic Price Pressures and October Rate Hike Expectations
On the domestic front, price pressures have shown a marked acceleration. Data compiled by MUFG indicates that India's consumer inflation climbed to 4.8 percent year-on-year in August, slightly below the DBS forecast of 4.9 percent but accelerating from the revised 4.5 percent print recorded in the preceding month. This reading marks the fastest pace of price expansion since December 2024. Economic analysts caution that a broadening of inflationary trends across core sectors is likely to keep headline inflation above 5 percent throughout the second half of the fiscal year, reinforcing the necessity for a more restrictive monetary framework.
The confluence of elevated crude oil import expenses, tightening worldwide financial liquidity, resilient domestic gross domestic product growth, and expanding core price metrics has fortified the rationale for a shallow 50-basis-point interest rate increase in the second half of fiscal year 2027. Consequently, the upcoming October monetary policy review has transformed into a critical decision point, with market participants assigning elevated probabilities to an active policy adjustment.
Technical Indicators and Chart Dynamics
From a technical charting standpoint, initial downside support for the USD/INR pair is anchored around the 20-day exponential moving average near 95.6104, where buying interest is anticipated to cushion potential retracements. Live technical indicators show the 14-period Relative Strength Index positioned at 55, while the MACD reflects positive momentum with a main line at 0.15 against a signal line of 0.09 and a bullish histogram reading of 0.07. Trend indicators demonstrate a long-term bullish bias with a golden cross formation, supported by the 20-day EMA at 95.54, 50-day EMA at 95.43, and 200-day EMA at 93.45, alongside the 50-day SMA at 95.51 and 200-day SMA at 93.73. The 20-period Bollinger Bands span from 94.21 to 96.47 with an average directional index reading of 34, indicating an established trend. On the topside, a decisive breakout above 96.00 would clear the path for a retest of the record high near 97.00. Near-term pivot points stand at 95.88, with overhead resistance at 95.94 and 96.03, and underlying support levels at 95.79 and 95.73.
Structural Drivers of Rupee Valuations
The valuation dynamics of the Indian Rupee remain uniquely exposed to international external shocks. As an economy heavily dependent on imported crude oil to satisfy domestic fuel requirements, escalating oil benchmarks directly worsen import bills and inflate demand for foreign exchange. Because global trade transactions are predominantly settled in US Dollars, dollar strength directly pressures the local currency, alongside the ebbs and flows of overseas investment capital.
To counteract sharp volatility, the Reserve Bank of India routinely engages in foreign exchange interventions, supplying dollars to preserve smooth market liquidity and shield commerce from currency shocks. In tandem, monetary authorities use policy interest rates to anchor domestic inflation near the statutory 4 percent target. Higher domestic yields historically support the Rupee through carry trade mechanisms, wherein international capital borrows in lower-rate jurisdictions to deploy assets into higher-yielding sovereign paper. Additional macro determinants include economic growth trajectories, trade balances, and foreign direct and institutional capital inflows, whereas relatively higher domestic inflation depreciates purchasing power parity and escalates export costs.
Broader Foreign Exchange and Commodity Crosscurrents
The strength of the US Dollar and high global yields reverberated across peer currency pairs and asset classes on Friday. The Australian Dollar (AUD/USD) slid to fresh multi-week lows, breaching its 200-day simple moving average to trade defensively near 0.7000 during Asian trading hours. Geopolitical uncertainties and a two-day oil price surge fueled broader inflation anxieties, lifting the dollar to two-month highs and overshadowing expectations of local policy tightening by Australia's central bank.
In foreign currency crosses, the US Dollar held steady against the Japanese Yen (USD/JPY) after a powerful run toward a three-week peak of 159.00 paused as traders grew wary of official currency market interventions. The Bank of Japan adjusted its short-term policy interest rate target upward from 1.00 percent to 1.25 percent in a 7-2 committee vote, proceeding with policy normalization in line with consensus expectations. Concurrently, spot Gold consolidated below $4,300 per ounce, extending a recovery from Thursday's low of $4,244 yet remaining on track for its steepest weekly decline in four weeks amid sustained pressure from surging global bond yields and firm Federal Reserve policy expectations.