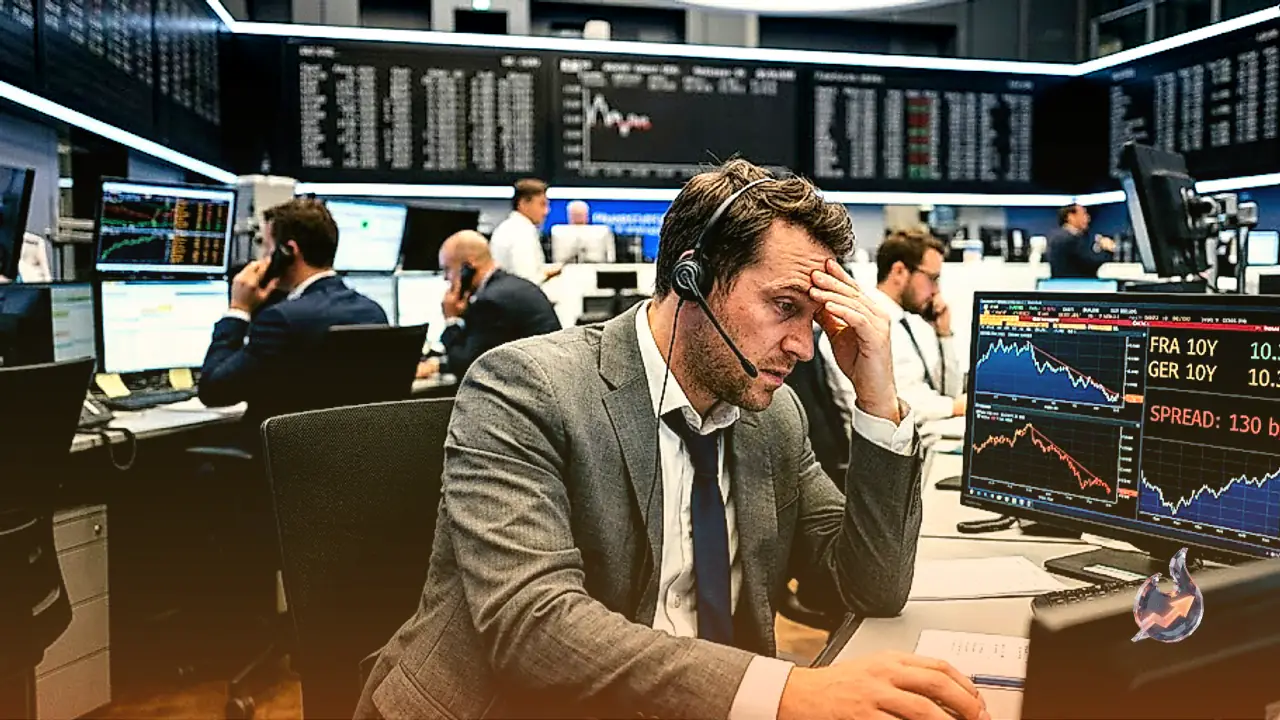















A steep sell-off swept across European foreign exchange markets as the Euro tumbled against the US Dollar, touching its weakest level since May 2025. Investor anxiety spiked after the spread between French and German ten-year government bond yields surged to 130 basis points, marking the widest divergence recorded since 2012. This yield gap reflects growing wariness among global lenders over sovereign debt risks. Driven by heavy liquidation, the EUR/USD pair drifted toward its sharpest single-session loss since June 17, slipping just beneath the 1.1250 mark in turbulent trading.
Fiscal Strain in Paris and Mounting Debt Costs
The immediate trigger for the bond market jitters arrived on Thursday when the government under Prime Minister Lecornu unveiled its proposed 2027 fiscal budget. The budgetary roadmap was intended to restore creditor confidence and demonstrate fiscal discipline. The political backdrop remains precarious, as both of Lecornu's immediate predecessors lost their positions over budget disputes. France has persistently run budgetary shortfalls exceeding 5% of its Gross Domestic Product (GDP). To contain future deficits within that 5% ceiling, the newly announced plan enforces a freeze on public-sector wages and halts adjustments across the vast majority of state pensions. However, investors demanded higher yield premiums, unwilling to ease their risk pricing.
European Central Bank Tightening Amplifies Sovereign Borrowing Pressures
The sovereign fiscal headaches in France intersect directly with an aggressive monetary policy stance maintained by the European Central Bank (ECB). Operating out of Frankfurt, Germany, the ECB raised its key deposit facility rate to 2.50% on September 10, delivering its second rate hike of the calendar year. Because Eurozone consumer inflation remains entrenched above 3%, money markets are actively factoring in further policy tightening. Each successive rate increase drives up the borrowing cost on newly issued French sovereign paper, compounding the annual cost of servicing national debt.
Market participants are now closely watching the release of the flash Harmonised Index of Consumer Prices (HICP) for September, scheduled for Friday at 09:00 GMT. Consensus expectations project headline inflation to accelerate to 3.6% year-on-year from 3.2%, with the core gauge expected to rise to 2.5% from 2.4%. Policy communication will surround the data release, with ECB Executive Board member Cipollone addressing markets beforehand and ECB Vice-President Vujčić speaking afterward. At 12:30 GMT, the release of US non-farm payroll figures will add further volatility. A hotter inflation print would bolster expectations for another ECB rate increase at its October 29 meeting. Crucially, preliminary September data released on Wednesday across Germany, France, Italy, and Spain all exceeded forecasts, leaving little doubt about broad inflationary momentum.
Technical Indicators and Key Price Thresholds
From a chartist perspective, EUR/USD surrendered a vital technical floor on Thursday by breaking below 1.1300, a level that had held firm since May 2025. An intraday rebound that attempted to regain the mark lost momentum just above the threshold, while the Thursday peak fell short of 1.1350 before aggressive selling resumed. Downward momentum brings the 1.1200 support line into immediate focus, sitting just below Thursday's trough. Beneath that lies the psychological level of 1.1150.
The prevailing technical bias remains bearish for daily closes below 1.1300, targeting initial support at 1.1200 followed by 1.1150. However, momentum oscillators highlight stretched conditions, with the daily Stochastic Relative Strength Index (Stoch RSI) hovering near 3, hugging the floor of its range and signaling extreme oversold conditions. A short-term counter-trend retracement toward 1.1300 around Friday's economic data would fit within this broader bearish setup. Only a daily settlement back above 1.1350 would invalidate the negative technical bias. Live price indicators show EUR/USD at 1.12, down 0.71% from its prior close of 1.13, with its 14-day RSI deep in oversold territory at 17, and a death cross pattern in play where the 50-day EMA sits below the 200-day EMA.
The Euro's Systemic Footprint and Influencing Drivers
The Euro functions as the shared currency across the 20 European Union member nations comprising the Eurozone. Ranking as the second most heavily traded currency on the planet behind the US Dollar, it accounted for 31% of all foreign exchange turnover in 2022, representing an average daily volume exceeding $2.2 trillion. The EUR/USD pair alone commands approximately 30% of global foreign exchange transactions, followed by EUR/JPY at 4%, EUR/GBP at 3%, and EUR/AUD at 2%.
Monetary authority resides with the ECB Governing Council, which convenes eight times annually to evaluate economic conditions and set borrowing costs. The council consists of six permanent members, including ECB President Christine Lagarde, alongside governors from the national central banks of Eurozone members. The bank's primary mandate focuses on price stability, balancing inflation containment against economic growth. Beyond inflation metrics, macroeconomic reports detailing GDP expansion, Manufacturing and Services PMIs, labor market employment, and consumer sentiment shape currency valuations. Economic prints from Germany, France, Italy, and Spain are particularly critical, given that these four economies account for roughly 75% of total Eurozone output. National trade balances also directly influence currency strength, where sustained net surpluses generate organic commercial demand for the Euro.
Cross-Asset Developments in Global Currency and Commodity Markets
The broader currency landscape reflected sustained dollar strength, exerting downward pressure across multiple asset classes. AUD/USD traded defensively, staging a mild bounce off three-month lows near 0.6900 prior to Friday's Asian open following weekly declines driven by general risk aversion. Concurrently, USD/JPY held near the top of its weekly range above 158.00 during Thursday's Asian trade, where elevated US Treasury yields linked to oil-related inflation risks countered Bank of Japan tightening speculation and currency intervention threats. The ongoing standoff between the United States and Iran further bolstered safe-haven flows into the US Dollar.
In commodities, spot gold lacked decisive traction on Thursday, remaining pinned below the $4,200 per troy ounce threshold amid mixed forces stemming from dollar strength and Middle Eastern geopolitical friction. Meanwhile, investor expectations regarding the Federal Reserve underwent a swift realignment. While financial markets viewed an October rate hike as probable just a week earlier, recent cooling inflation data and cautious official commentary have shifted the prevailing baseline toward an interest rate pause.