
















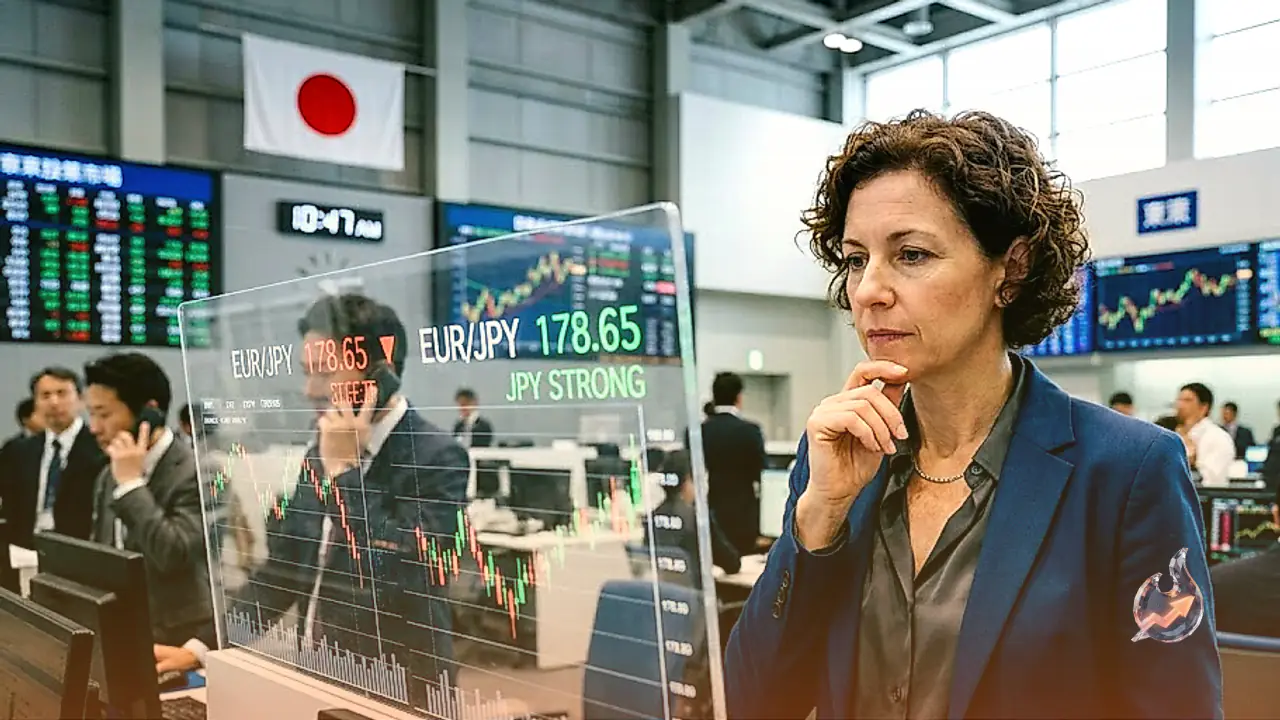

A resurgence in demand for the Japanese currency pushed the common European unit lower on Thursday, breaking a three-session streak of gains across international foreign exchange desks. The EUR/JPY exchange cross retreated by 0.25 percent, changing hands near 178.70 as sellers took charge and drove trading underneath the critical 179.00 mark. Market participants are positioning themselves ahead of an imminent monetary policy review in Tokyo, where expectations for higher borrowing costs continue to build.
Anticipation Around Tokyo Monetary Tightening and Official Caution
Trading desks widely anticipate that the Bank of Japan will implement an increase of 25 basis points to its policy benchmark rate during Friday's gathering. Such an adjustment would represent another progressive departure from decades of ultra-loose monetary mechanisms. Despite aggressive positioning in futures markets, Tokyo officials maintained an intentionally measured posture during public remarks on Thursday.
Japan's Economy Minister Minoru Kiuchi stated that government policy is oriented toward reconciling economic resilience with sustainable public finances, while declining to offer direct guidance on the interest rate trajectory. In parallel remarks, Finance Minister Satsuki Katayama stated that authorities plan to scrutinize budget allocations and manage sovereign debt sales prudently to sustain investor faith. Katayama noted her expectation that the monetary authority will guide its instruments appropriately so that the two percent price increase benchmark is reached stably.
Eurozone Inflation Figures Fall Short of Fueling Single Currency
Developments across continental Europe did little to stem the downward pressure on the single currency. Official figures showed that the Harmonized Index of Consumer Prices climbed 0.4 percent month over month, aligning precisely with both consensus forecasts and the earlier period's growth pace. Over the full twelve months, consumer inflation receded slightly to 3.2 percent, undershooting the anticipated 3.3 percent reading.
Core consumer measurements matched analyst consensus without deviation, yet the broader deceleration left the Euro without sufficient upward traction against surging Asian peers. Across broad currency rankings, the Euro demonstrated its best performance against the Canadian Dollar, while struggling to hold ground against currencies supported by shifting central bank expectations.
Cross-Asset Movements in Currencies, Commodities, and Yields
Activity across alternative currency pairs reflected broader macro adjustments on Thursday. The Australian Dollar regained traction during Asian hours, climbing back over 0.7100 as the US Dollar index paused following a sharp post-Fed ascent that had taken it to levels unseen since late July. Support for the Australian Dollar emerged from local policy tightening projections by the Reserve Bank of Australia, alongside investor optimism surrounding diplomatic interactions between Washington and Tehran.
Meanwhile, the USD/JPY rate recovered after dipping under 156.00 in Asian dealing, threatening to break a three-day winning momentum that had reached nearly two-week highs. With the greenback taking a breather following its rise to seven-week peaks, aggressive market repricing around Japanese policy normalization provided clear underlying support for the Yen, curtailing further topside expansion ahead of the central bank outcome.
In commodities, spot gold prices mounted a rebound throughout the early segment of European trading. The precious metal clawed back value from an intraday low that had brought it near six-week troughs during the previous session. A minor retracement in US government bond yields triggered profit-taking in the dollar, offering breathing space to the metal. However, lingering hawkish sentiment surrounding the Federal Reserve and heightened geopolitical friction in the Middle East worked to place a ceiling on gains for non-yielding bullion.
The Shifting Landscape of Global Carry Trades
For more than ten years, ultra-depressed borrowing charges in Japan served as the cornerstone for financing trillions of dollars in worldwide asset allocations, cementing the Yen's standing as one of the planet's least expensive funding instruments. While competing global economies embarked on aggressive tightening campaigns to rein in price pressures, Japan stayed an unprecedented global anomaly. With the central bank poised to raise its benchmark again, this historical financing advantage appears to be crossing into an entirely transformed era.