















Registration momentum across India's electric two-wheeler segment experienced a noticeable slowdown during August 2026. Total monthly volumes dropped by 10.35 percent compared to the prior month. Across the country, dealerships had dispatched 2,04,362 vehicles during July 2026, but the total volume fell to 1,83,204 units in August. That represented a net contraction of 21,158 registrations within a single thirty-day span, even as established vehicle giants managed to maintain their industry rankings.
Festive Timing and Inventory Control Impact Volumes
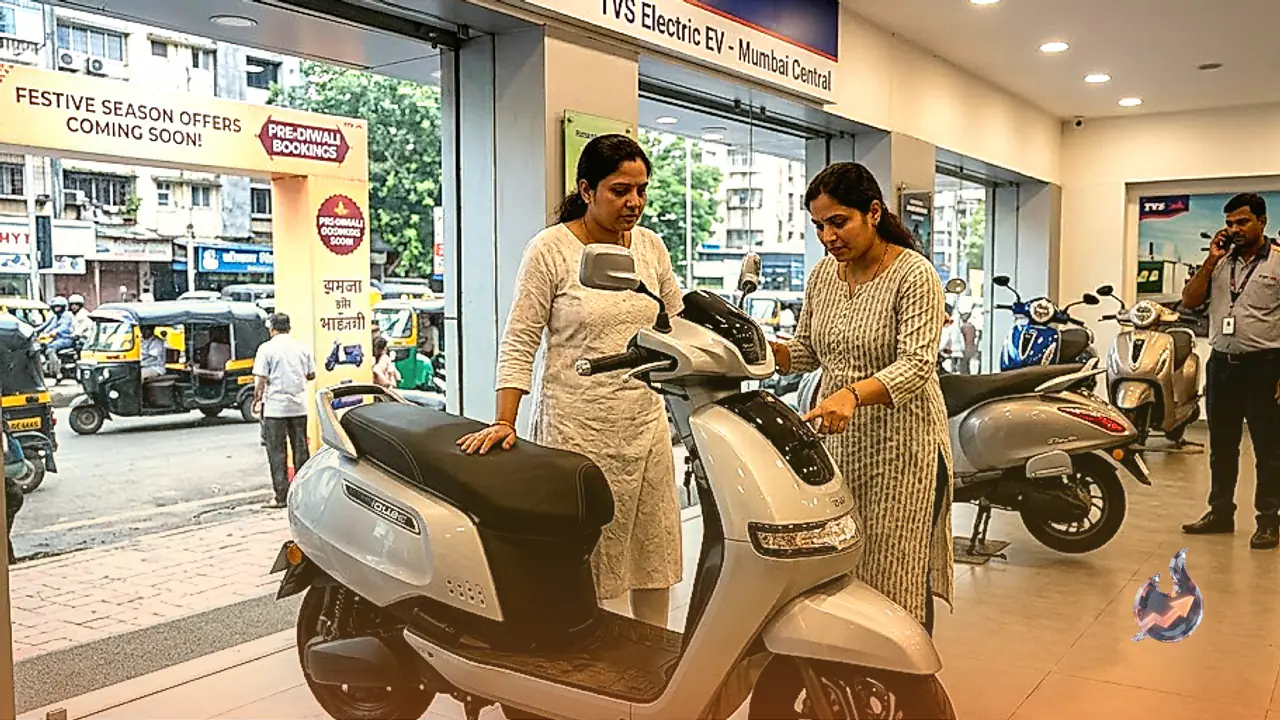
The downturn cut across every manufacturer tier, pulling down both high-volume leaders and boutique electric brands into negative growth. Industry observers pointed toward widespread customer hesitation ahead of the autumn festive period, as buyers delayed showroom visits to await seasonal discount programs. At the retail level, dealership networks actively slowed fresh vehicle intakes to optimize floor inventories before peak holiday restocking cycles commenced.
TVS Motor and Bajaj Auto Retain Top Positions
TVS Motor Company maintained its leadership over the national market by delivering 48,938 units during the month. When measured against its July dispatch of 55,499 vehicles, the company weathered an 11.82 percent drop, representing 6,561 fewer units. Having secured a 27.16 percent overall market share in July, sustained customer interest in its iQube lineup allowed the brand to protect its number-one ranking.
Bajaj Auto claimed the second position by delivering 41,114 electric two-wheelers. That compared with 45,613 Chetak scooters delivered during July, marking a 9.86 percent decline equivalent to 4,499 fewer units. Retaining a 22.32 percent slice of the market from July, Bajaj relied on fresh variants and an expansive service network to hold its spot firmly in the top two.
Performance of Ather Energy, Hero Vida, and Ola Electric
Ather Energy secured the third spot with 28,757 registered units, retreating 5.27 percent or 1,600 vehicles from the 30,357 delivered in July. Supported by a 14.85 percent market share in July, Ather witnessed significantly milder contractions than most competitors, reflecting resilient retail appetite for its Rizta family scooter and 450 series lineup.
Hero Vida ended in fourth position, suffering the sharpest double-digit slide among the top group. Its monthly tally slumped 17.00 percent or 3,893 units to 19,007 vehicles, falling from 22,900 units in July when its market share stood at 11.21 percent. Fifth-placed Ola Electric delivered 13,852 vehicles, slipping just 1.80 percent or 254 units from 14,106 in July. That made Ola the most stable performer in the top tier, following its 6.90 percent market share in July.
Greaves Ampere and Other Manufacturers Complete the Board
Further down the rankings, sixth-placed Greaves Ampere dropped 14.93 percent to register 8,613 units. River claimed the seventh position with a 13.65 percent reduction to 5,141 units, while BGauss captured eighth place by posting a 12.20 percent slide to 4,845 units. The remaining collection of smaller regional manufacturers collectively contracted by 9.47 percent, recording 12,937 units.