














Global equity markets took a positive turn on Friday as retreating crude oil prices and softer US Treasury yields revived risk appetite among investors. The pullback in energy costs helped alleviate immediate inflation anxieties, encouraging fresh buying across US stock index futures. The upward trajectory followed a resilient session on Wall Street, with pre-market indicators pointing to extended momentum during European trading hours.
US Futures Advance Across Major Benchmarks
Dow Jones futures gained 0.25% to trade in the vicinity of 51,940 during European dealing on Friday. Meanwhile, S&P 500 futures rose 0.34% to change hands around 7,670, and tech-heavy Nasdaq 100 futures outperformed with a 0.64% increase, trading near 29,630. This upward drift in futures contracts built directly upon the broad-based gains logged during Thursday's standard trading session.
Thursday's Tech Surge and Semiconductor Recovery
During regular trading on Thursday, major US equity indices logged decisive advances. The Dow Jones Industrial Average added 0.61%, the broad S&P 500 climbed 1.14%, and the technology-focused Nasdaq Composite paced the broader market with a 1.69% jump. Semiconductor manufacturers served as the primary growth engine for the rally, staging an assertive comeback from recent sell-offs.
Earlier pressure on the semiconductor sector had been triggered by artificial intelligence safety concerns, which momentarily injected hesitation regarding the sustainability of corporate capital expenditure in AI infrastructure. However, investor confidence quickly returned to the hardware ecosystem. Pronounced gains were recorded across leading chipmakers and hardware specialists, including Micron, Nvidia, Intel, AMD, and SanDisk.
Monetary Policy Shifts and Treasury Yield Pressure
Despite the equity rebound, financial markets continue to navigate persistent monetary headwinds. Hawkish remarks from Fed Chair Warsh have sharply recalibrated interest rate projections, pushing expectations for an October interest rate hike up to 53.1%. While a higher borrowing environment typically weighs on risk assets, the immediate pressure was counterbalanced by a retreat in US bond yields from their recent multi-year highs. The cooling of crude oil markets provided much-needed relief from fears of runaway inflation, stabilizing fixed-income assets and supporting equity valuations.
Structure and Composition of the Dow Jones Industrial Average
The Dow Jones Industrial Average stands among the oldest equity benchmarks globally, designed to track 30 of the most actively traded corporate leaders in the United States. Distinct from capitalization-weighted gauges, the Dow is a price-weighted index. It is computed by summing the nominal share prices of its 30 component companies and dividing that total by a mathematical divisor, which currently stands at 0.152.
The benchmark was originally created by Charles Dow, who also founded the Wall Street Journal. Over the decades, market commentators have noted limitations in its methodology, pointing out that an index composed of only 30 conglomerates offers a narrower snapshot of the broader financial landscape compared to comprehensive indices such as the S&P 500.
Primary Drivers of the Dow Jones Index
A diverse set of microeconomic and macroeconomic forces governs the performance of the Dow Jones Industrial Average. Foremost among them is corporate earnings, as revealed in the quarterly financial reports released by the 30 component corporations. Solid revenue generation and expanding profit margins naturally lend support to index pricing.
Broader macroeconomic indicators across the US and international economies also play a substantial role by shaping institutional and retail sentiment. Interest rate policy established by the Federal Reserve carries immense weight because it directly dictates the cost of corporate borrowing. Given that major corporations depend heavily on liquid credit lines to sustain operations and capital investments, higher rates can compress margins. Consequently, consumer inflation figures and the broader economic data points that steer Fed policy decisions remain critical barometers for the index.
Dow Theory Principles and Trend Identification
Technical analysis continues to utilize the Dow Theory, an analytical framework conceived by Charles Dow to discern the underlying primary direction of financial markets. A fundamental premise of the doctrine requires comparing the trajectories of the Dow Jones Industrial Average (DJIA) and the Dow Jones Transportation Average (DJTA). Under this framework, a primary trend is only considered verified when both the industrial and transportation indices are traveling in alignment.
Trading volume serves as a confirming metric within the theory, which also incorporates peak and trough price evaluations. Dow Theory divides major market moves into three distinct stages. The initial phase is accumulation, occurring when sophisticated institutional investors or smart money systematically enter or exit positions. This is followed by the public participation phase, during which the broader retail investing community observes the trend and commits capital. The sequence concludes with distribution, where smart money liquidates holdings into peak market liquidity as the prevailing trend matures.
Investment Vehicles for Trading the Dow Jones
Market participants access the Dow Jones Industrial Average through multiple financial instruments tailored to diverse strategies. Exchange-traded funds (ETFs) remain one of the most accessible avenues, allowing participants to trade the entire index as a unified asset rather than acquiring 30 individual equity holdings. A prominent example is the SPDR Dow Jones Industrial Average ETF (DIA).
For leveraged trading and hedging, DJIA futures contracts allow market players to speculate on future index valuations. Options contracts offer another mechanism, providing the legal right without the obligation to purchase or sell the index at an agreed-upon strike price before expiration. Additionally, conventional mutual funds offer fractional participation in diversified equity pools replicating the 30 constituent holdings, giving long-term investors hands-off exposure to the blue-chip gauge.
Global Forex Movements and Commodities Reaction
Cross-market ripple effects from softer Treasury yields were distinctly felt in global currency and commodity trading. In the Asian session on Friday, AUD/USD maintained positive momentum for the second consecutive day, holding firmly above 0.7100. Lower US yields kept dollar bulls constrained, while hawkish commentary from RBA Governor Bullock bolstered Australian rate hike expectations. However, gains in the currency pair were ultimately capped by geopolitical uncertainties and the overarching hawkish guidance from the Federal Reserve.
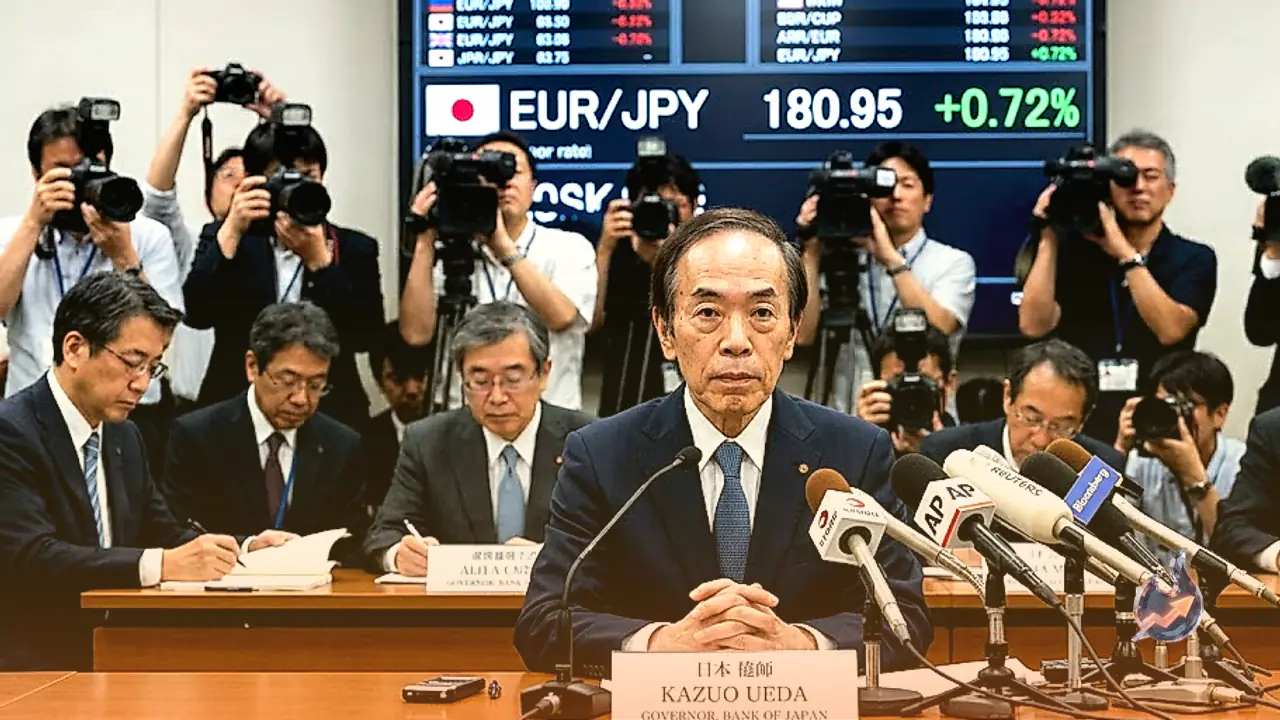
In Europe, USD/JPY pulled back from two-week highs near 157.30 as the Japanese Yen gained ground following remarks by Bank of Japan Governor Ueda during his post-meeting press conference. Earlier in the session, the Bank of Japan surprised markets with a 7-2 vote to raise its policy interest rate to 1.25%.
For more than a decade, Japan's ultra-loose monetary posture provided virtually free liquidity that funded trillions of dollars in international investments, cementing the yen as a primary funding currency for global carry trades. As the Bank of Japan steps toward further policy normalization, that prolonged funding advantage is entering a transformative era, shifting Japan away from its position as a global monetary outlier.
Commodities also capitalized on dollar softness, with spot gold extending its advance into a second session to reach a fresh weekly peak entering European hours. The pullback in crude oil prices diminished acute inflation fears, driving Treasury yields down from recent highs and clearing the path for bullion to attract steady bids.