














MUFG expects stronger electronics exports to provide only partial support to the Thai baht, leaving the currency exposed to a wider set of domestic and external pressures. Its year-end USD/THB forecast remains 34.00, reflecting concern that export strength will not overcome weak growth, low interest rates, persistent portfolio outflows, worsening trade conditions and tighter fiscal room.
The case behind the 34.00 forecast
MUFG says Thailand is gaining from the technology cycle, but it does not view the resulting rise in electronics shipments as sufficient to neutralize the broader drag. The headwinds include deteriorating terms of trade, subdued growth, low rates, sustained portfolio outflows and fiscal constraints that are becoming more restrictive.
That combination matters because a currency's external position depends on more than gross export sales. An export boom can still leave the external account strained when many of its required inputs are purchased abroad. Import costs, investment flows, available yields and the government's capacity to absorb shocks determine how much support ultimately reaches the baht.
Where the electronics gains are absorbed
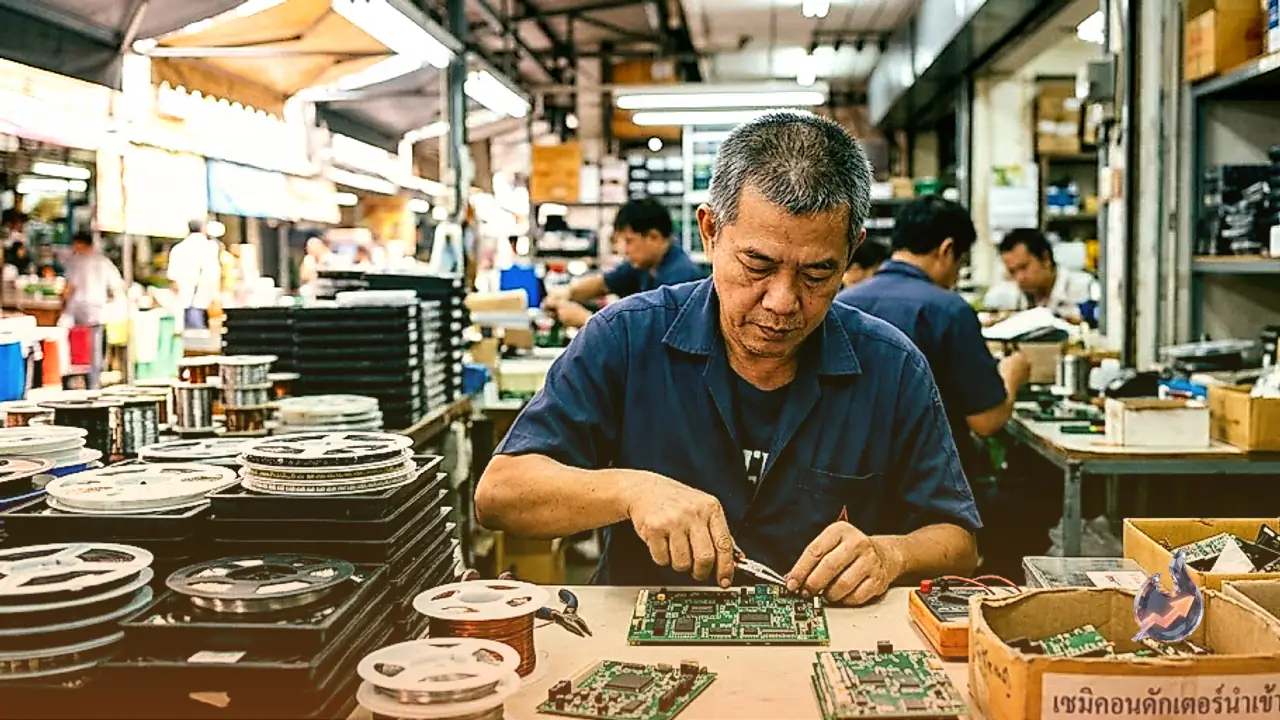
Thailand buys more semiconductors from abroad than it sells, and those chips are essential for electronics production. When export activity expands, producers therefore still need substantial foreign currency to obtain the required inputs.
As chip prices climb and the foreign-made share of products rises, the electronics import bill expands. Net trade gains then remain smaller than the export headlines suggest, which is why MUFG sees less foreign-currency support for the baht than headline growth appears to offer.
Commodity costs weaken external balances
The strain extends beyond chips to a wider commodity shock involving energy, metals and intermediate goods. Higher prices for these purchases are weighing on Thailand's external balances.
Terms of trade have slumped to their lowest level in 27 years. The oil shock is especially difficult to absorb because fiscal room is limited, leaving less public capacity to cushion its effect. In a weak-growth environment, this further reduces the trade cushion even while electronics output appears to be expanding.
Rate gap and portfolio flows add pressure
Thailand's central bank holds its policy rate at 1.0%, a level MUFG expects to persist into early 2027. The Fed has already increased rates and may impose additional tightening over the coming months.
Low local rates, an overvalued baht and persistent net foreign portfolio outflows reinforce one another. With fiscal space also constrained, the economy has less room to counter the oil shock. The outlook therefore gives more weight to net flows and purchasing power than to the export headline alone, leaving MUFG cautious on THB.
Asian-session moves in currencies and gold
AUD/USD picked up new buying interest and reclaimed 0.7100 during Thursday's Asian session. The US dollar paused after a hawkish, Fed-driven rally had lifted it to its highest point since late July. Bets on an RBA rate increase and optimism about US-Iran diplomatic efforts improved risk sentiment, supporting the risk-sensitive Australian dollar and AUD/USD.
USD/JPY recovered from a short fall beneath 156.00 in Thursday's Asian trading and looked ready to end a three-day winning run that had reached a nearly two-week high the previous day. The dollar paused after its post-Fed advance to seven-week highs, while a more hawkish market reassessment of the BoJ's policy-normalization path supported the yen. That capped the pair's upside and shifted attention to the BoJ decision due Friday.
Gold advanced strongly and established fresh weekly peaks on Thursday, although the rally encountered an initial barrier near the $4,400-per-troy-ounce zone. The rebound ended three straight daily declines. It also followed a modest pullback in the US dollar and another negative showing from crude oil prices.
Central-bank signals sharpen the contrast
At 3.75%, Bank Rate was held steady by the Bank of England, although its communication was distinctly hawkish as the inflation outlook deteriorated sharply.
In a unanimous vote, the Fed lifted the Fed Fund Target Range (FFTR) by 25 basis points, setting it at 3.75%-4.00%. It said the action would help bring inflation back to the 2% goal sooner.
For over a decade, exceptionally low rates in Japan supplied trillions of dollars in financing for investments around the world. That made the Japanese yen among the least expensive funding currencies globally. With the Bank of Japan expected to tighten again this week, that advantage may be moving into a new phase; most major economies have raised rates, while Japan has remained the outlier.
The broader signal for currency investors
Across these markets, rate expectations and dollar moves are reshaping positions. Thailand's export gains are being absorbed by imported chips and commodity costs, while low rates and capital outflows persist. By contrast, possible BoJ tightening is supporting the yen, RBA hike expectations are aiding the Australian dollar, and gold is responding to a softer dollar and weaker crude. None of these moves changes the stated 34.00 USD/THB forecast, but they show why currency investors are watching central banks, input costs and foreign flows together.