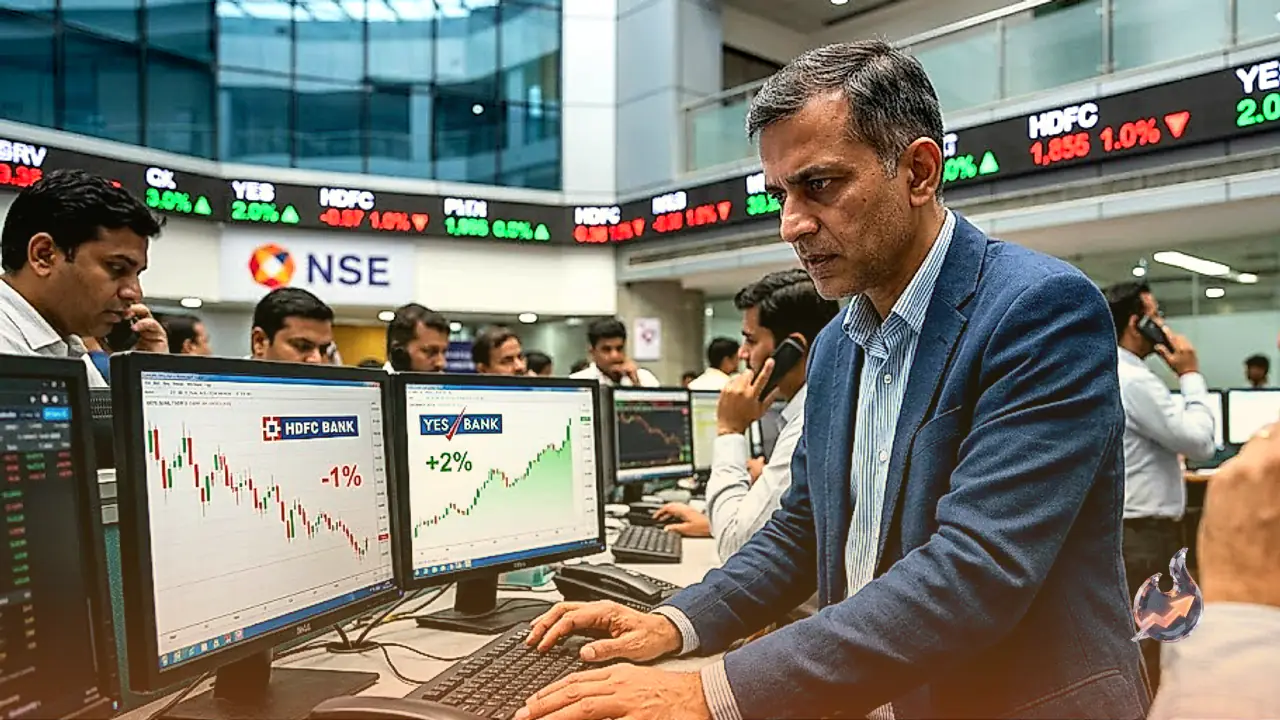














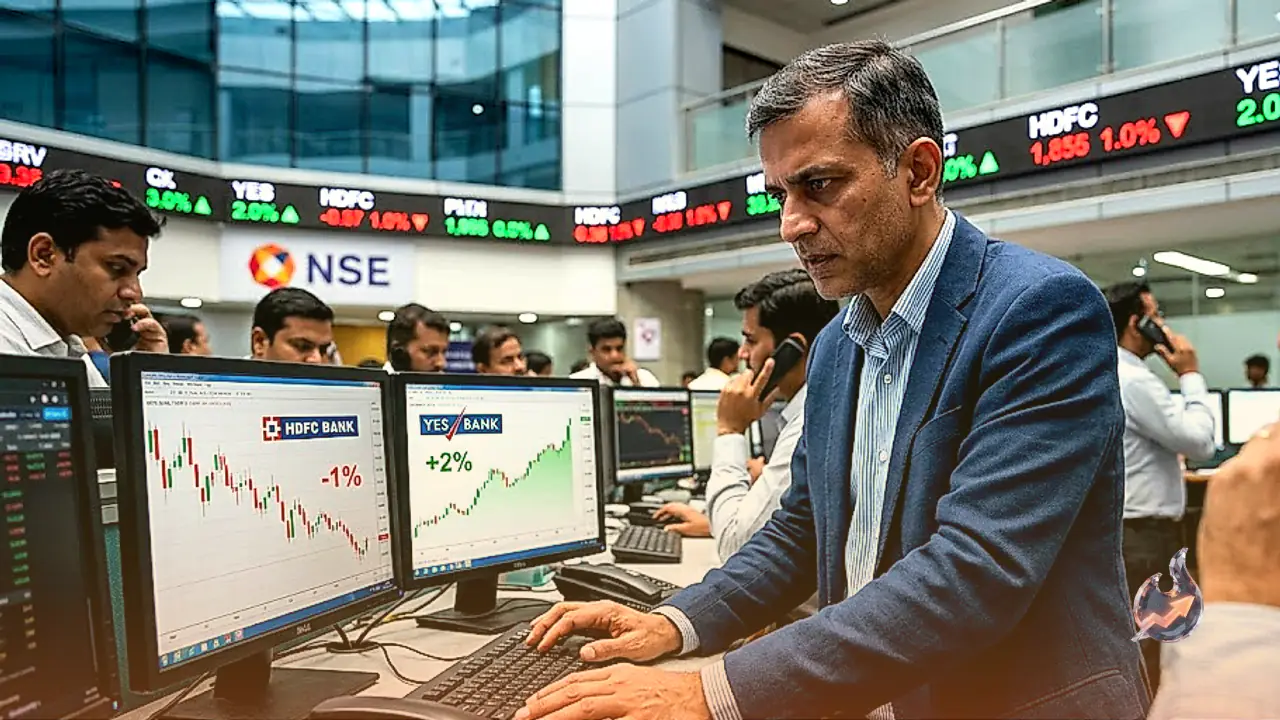

Early trade on Monday witnessed divergent price trajectories for two prominent Indian private lenders after both institutions released their quarterly operational performance updates for the second quarter of FY27. HDFC Bank slipped roughly 1% as market participants factored in ongoing transitions and underlying balance sheet metrics, even while loan book and deposit expansions held firm. In contrast, Yes Bank managed an advance of nearly 2%, reacting to robust double-digit expansion across its overall lending portfolio and customer deposit base.
HDFC Bank Navigates Selling Pressure Following Q2 Performance Metrics
Shares of HDFC Bank traded around Rs 714.60 each on the NSE during the morning session, marking a decline of nearly 1% and hovering close to the intraday trough of Rs 713 apiece. The pullback unfolded despite the lender posting a 18.8% year-on-year surge in overall deposits for the quarter ended September 2026, taking the total aggregate to Rs 33,275 billion against Rs 28,018 billion recorded in the corresponding period of FY26.
On the credit side, total gross advances advanced 16.3% year-on-year to reach Rs 32,195 billion as of Q2FY27, up from Rs 27,692 billion reported in Q2FY26. Advances under management for the institution reached Rs 33,075 billion over the same quarterly span, translating into a 15.3% growth trajectory. Additionally, the bank's average current account and savings account deposits rose 10.7% year-on-year to touch Rs 9,712 billion for the September 2026 quarter.
Balance Sheet Nuances, Foreign Currency Deposits, and Leadership Transition
A research note from Jefferies broken down the quarterly trajectory, highlighting that HDFC Bank demonstrated 16% loan growth, 19% deposit growth, and 11% CASA expansion for the September 2026 quarter. These figures outpaced the corresponding prints of 15%, 15%, and 9% recorded in the preceding June quarter. The lender's loan-to-deposit ratio held at 97%. Balance sheet expansion received an incremental push from $11.5 billion in FCNR-B deposits, with $5.7 billion originating via credit, accounting for approximately 3.3% of total deposits and 1.7% of overall loans.
Broader market sentiment around the heavyweight was also influenced by the executive appointment of Anup Bagchi as the new chief executive officer. Bagchi, previously associated with ICICI Group, brings three decades of executive track record spanning banking operations, insurance, wealth management, and capital markets. Investors and market watchers are closely tracking how the institution navigates this top-level leadership handover alongside execution across major banking verticals.
Yes Bank Gains Momentum on Double-Digit Credit and Deposit Expansion
In contrast to the softness seen in the benchmark private lender, Yes Bank shares added approximately 2% to trade around Rs 21.11 apiece on the NSE. The movement positioned the equity near its intraday high of Rs 21.23 and within range of its 52-week peak of Rs 25.78 apiece. Operational figures for Q2FY27 revealed that Yes Bank generated a 23.8% year-on-year jump in loans and advances to Rs 309,675 crore, while overall deposit mobilization grew 19.5% year-on-year to reach Rs 354,084 crore.
Despite the headline loan momentum, underlying liability composition exhibited some compression. Yes Bank's CASA ratio retreated to 30% in Q2FY27, down from 32.7% logged in Q1FY27 and 33.7% seen in Q2FY26. On the liquidity front, the bank's liquidity coverage ratio stood at 131.4% during Q2FY27, expanding from 125.1% in Q2FY26 but easing sequentially from 138.2% recorded in the April to June 2026 quarter.
Analyst Recommendations and Valuation Forecasts
Market evaluations of both banking names show contrasting views among brokerage desks. Jefferies remained constructive on HDFC Bank despite the immediate stock pullback, projecting FY27 estimated loan and deposit growth at 13% and 15% respectively. The brokerage noted that following the leadership appointment of Anup Bagchi, attention will pivot toward leadership transition and the medium-term roadmap, backing the counter with a BUY recommendation and a target price of Rs 880.
Conversely, broad consensus coverage on Yes Bank skews more cautious. Data compiled by Trendlyne indicates that a collective consensus of 13 analysts maintains a SELL rating on Yes Bank equity. Their consensus target price stands pegged at Rs 21.15 per share, aligning almost exactly with the current trading territory and signaling limited anticipated room for near-term multiple expansion.