
















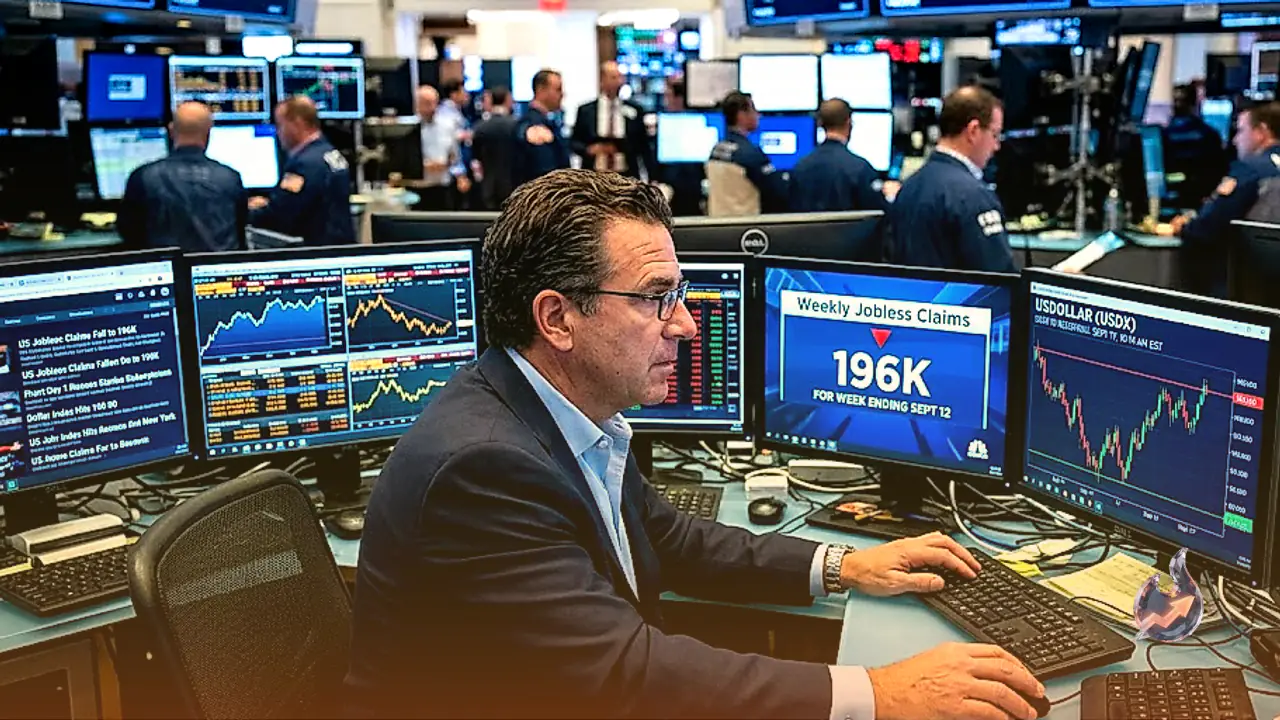

Fresh labor market metrics from the United States have highlighted resilient employment conditions, sending noticeable ripples across global foreign exchange and commodities trading desks. Initial claims for unemployment insurance dropped to 196K for the week ending September 12, according to data published on Thursday by the US Department of Labour (DOL). The reading came in lower than consensus forecasts of 208K and marked a clean drop from the previous week's unrevised figure of 206K. Concurrently, continuing jobless claims dropped to 1.730M, reinforcing that the broader pool of ongoing claimants is also experiencing contraction.
Weekly Labor Metrics and Four-Week Moving Average
Smoothing out the week-to-week volatility, the four-week moving average of initial jobless claims decreased by 2.75K to settle at 203.25K, down from the prior week's unrevised average. Policymakers and market analysts heavily rely on this multi-week metric to extract underlying trends in corporate hiring and workforce retention without the distortions of single-week noise. The ongoing decline suggests that employers across the American economy remain reluctant to lay off staff in significant numbers.
Despite the constructive labor print, the Greenback has been retreating from its recent peak levels. The US Dollar Index (DXY) dropped toward the critical 100.00 psychological and technical contention zone, as market participants reassessed their positions following the post-Federal Reserve rally.
The Critical Nexus Between Employment, Inflation, and Currency Valuation
Labor market strength acts as a cornerstone for evaluating the broader vitality of an economy, functioning as a primary catalyst for currency valuations. Robust employment levels directly bolster consumer sentiment and household spending, serving as an engine for domestic economic expansion while underpinning the local currency. When the labor market runs tight—a condition marked by an acute shortage of workers to fill open vacancies—upward pressure quickly transmits to wage growth and broader inflation. Excess demand combined with restricted labor supply inevitably compels firms to offer higher compensation packages.
The trajectory of salary growth represents a vital gauge for central bankers. Accelerated wage gains equip households with elevated disposable income, which typically feeds into higher retail prices across consumer goods and services. Unlike transitory inflationary pressures driven by volatile energy markets, wage growth is widely viewed by economists as an embedded, structural component of persistent core inflation because businesses rarely reduce base salaries once implemented. Consequently, central banks globally track wage dynamics with acute scrutiny when calibrating benchmark lending rates.
Divergent Central Bank Mandates
Monetary authorities approach labor conditions through the prism of their distinct legal mandates. Some institutions carry explicit statutory obligations toward employment alongside inflation targets. The US Federal Reserve operates under a dual mandate that requires it to pursue maximum employment while preserving price stability. Under this framework, shifts in payroll figures and jobless claims directly shape the path of interest rate deliberations.
In stark contrast, the European Central Bank (ECB) adheres to a singular, hierarchical mandate strictly focused on price stability and maintaining inflation within targeted thresholds. Nonetheless, central banks across both sides of the Atlantic monitor employment trends closely, as the state of the workforce remains an indispensable barometer of domestic economic health and an immediate precursor to consumer price pressures.
Movements Across Global Forex, Japanese Yen, and Gold
The pause in the US Dollar's post-Fed advance triggered significant realignments across international asset classes. AUD/USD captured fresh buying interest during Thursday's Asian trading session, reclaiming the 0.7100 mark after the Greenback halted its rally that had reached late-July highs. Upward repricing of Reserve Bank of Australia (RBA) rate-hike expectations, paired with growing optimism regarding US-Iran diplomatic avenues, elevated broad market risk appetite and underpinned the risk-sensitive Australian currency.
Meanwhile, USD/JPY rebounded from a brief dip beneath 156.00 in Asian trade, attempting to halt a three-day winning streak that had carried the pair to a nearly two-week peak on the prior day. According to live market data, USD/JPY trades at 156.85, up 0.46% from the prior close of 156.13. The currency pair holds a 52-week trading span between 146.61 and 163.98, with volume tracking at 1.00x its 20-day moving average. Technical gauges show a 14-day RSI of 49 and a MACD reading of -1.05 against a signal line of -1.24, producing a bullish histogram reading of 0.19. The pair's exponential moving averages sit at 156.47 (EMA20), 158.10 (EMA50), and 157.62 (EMA200), reflecting a golden cross (EMA50 above EMA200) despite an overarching long-term downtrend. Bollinger Bands range from 151.92 to 161.61, the 14-day ADX registers 39 indicating an active trend, and the 14-day ATR sits at 1.47, highlighting day-to-day volatility parameters.
Gains in USD/JPY remain capped as market expectations price in a firmer normalization trajectory by the Bank of Japan (BoJ), with global focus pivoting toward Friday's upcoming BoJ monetary policy announcement. For more than ten years, Japan's ultra-low interest rate regime provided trillions of dollars in low-cost financing for global investment ventures, establishing the Yen as a primary vehicle for international funding. As the BoJ prepares to tighten policy further while other major global central banks navigate rate pauses, this multi-year financing advantage faces structural changes.
In the commodities space, Gold staged a sharp reversal, advancing toward the $4,480 per troy ounce region on Thursday. The yellow metal snapped three consecutive sessions of declines, capitalizing directly on the marked retracement in the Greenback and sustained downward pressure in crude oil benchmarks.