















A broad-based retreat in the Japanese Yen is providing strong upward momentum for the British Pound, allowing the GBP/JPY cross to climb higher in global currency markets. The deep interest-rate divide separating the United Kingdom from Japan remains the primary catalyst keeping sterling heavily favoured over the yen. Although the Bank of Japan has initiated a gradual path toward tighter monetary policy, the inflationary fallout from ongoing hostilities in the Middle East has compelled major central banks elsewhere to maintain restrictive monetary stances. This dynamic keeps interest-rate spreads persistently wide, preserving downside pressure on the Japanese currency.
Contrasting Monetary Views Within the Bank of England
Fresh remarks from Bank of England policymakers highlighted sharp internal disagreements regarding the appropriate path for British interest rates. Monetary Policy Committee member Swati Dhingra delivered a dovish assessment, stating that financial conditions have done a lot of tightening work already in the UK and pointing out that broad-based price rises comparable to the inflationary wave of 2022 are no longer being observed. However, Dhingra specifically noted that winter energy prices will be critical for second-round effects on inflation.
Presenting a far more hawkish outlook, Deputy Governor Clare Lombardelli argued that domestic wage growth remains too high to be consistent with the central bank's inflation target. Lombardelli warned that monetary policy is increasingly likely to need to tighten further if elevated energy prices persist without clear evidence of disinflation or weaker economic activity. She added that the justification for an interest rate hike grows stronger the longer the geopolitical conflict in the Middle East persists, reflecting mounting concerns over prolonged cost pressures.
Intervention Risks and Broader Currency Adjustments
While the UK-Japan yield gap offers steady support to GBP/JPY, broader currency flows remain tightly tethered to the movement of USD/JPY, particularly as the pair edges back toward the sensitive 160 psychological barrier where market intervention by Tokyo authorities becomes highly probable. During Asian trading, USD/JPY pulled back from three-week highs, stabilizing near 158.00. Rising domestic Japanese government bond yields and growing wariness of currency market intervention helped cushion the Yen, while the US Dollar sustained overnight gains near a two-month peak, underpinned by firm US Treasury yields and resilient bets on a hawkish Federal Reserve. Across the currency board, the Yen exhibited its strongest relative daily performance against the Swiss Franc.
Central Bank Moves Across Japan and Switzerland
The Bank of Japan pushed forward with policy normalisation, lifting its short-term interest rate target from 1.00% to 1.25% in a 7-2 vote. The decision closely aligned with broad market expectations built over several weeks, marking an incremental shift away from its ultra-loose framework. Even with the move, nominal lending rates in Japan remain exceptionally low compared to the rest of the developed world, limiting the Yen's ability to mount a sustained recovery.
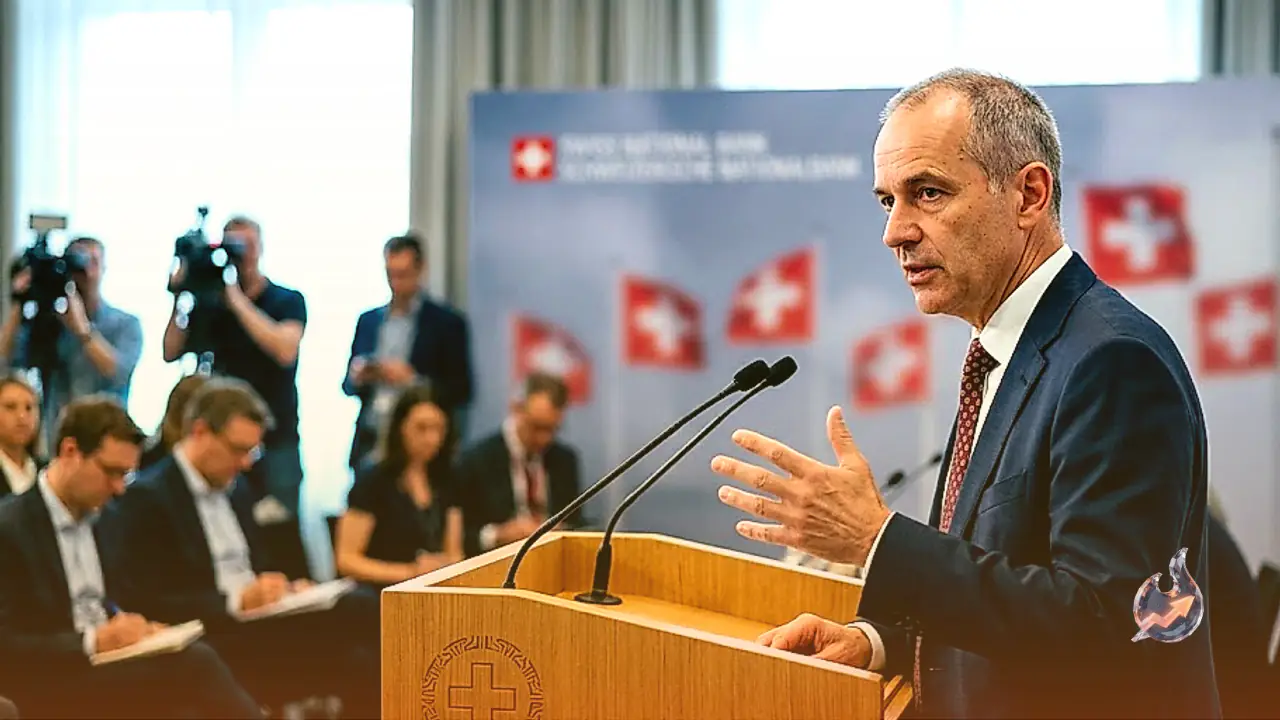
Meanwhile, the Swiss National Bank decided to leave its benchmark policy rate steady at 0%, fulfilling projections held by financial analysts. In its monetary policy assessment, the central bank confirmed that sight deposits held by commercial banks at the SNB will continue to be remunerated at the official policy rate up to a designated threshold. On the inflation front, the SNB adjusted its projection for 2026 upward to 0.7%, compared to its prior forecast of 0.6%. Swiss policymakers reiterated that the principal downside risks to Switzerland's domestic economic outlook originate from vulnerabilities and developments in the broader global economy.
Labour Data and Diplomatic Focus Shape Broader Markets
Other major currency pairs and commodities also reflected shifting macro sentiment. AUD/USD softened toward the 0.7000 threshold during Asian trading following the publication of Australia's August labour market report. The release showed the domestic unemployment rate ticking up to 4.6% against a consensus projection of 4.5%, even though net employment change exceeded expectations with an addition of 39.5K positions. Market participants also adopted a cautious posture ahead of an anticipated summit between US President Donald Trump and Chinese President Xi Jinping.
In commodities, gold extended its negative momentum for a second consecutive session, slipping beneath $4,300 to trade at a one-week trough during early European dealing. Precious metal investors remained focused on the forthcoming dialogue between Donald Trump and Xi Jinping. While overall expectations for an expansive bilateral breakthrough remain subdued, traders are monitoring the talks closely for concrete updates on rare earth minerals, high-technology trade curbs, and the possible prolongation of the prevailing US-China trade truce.