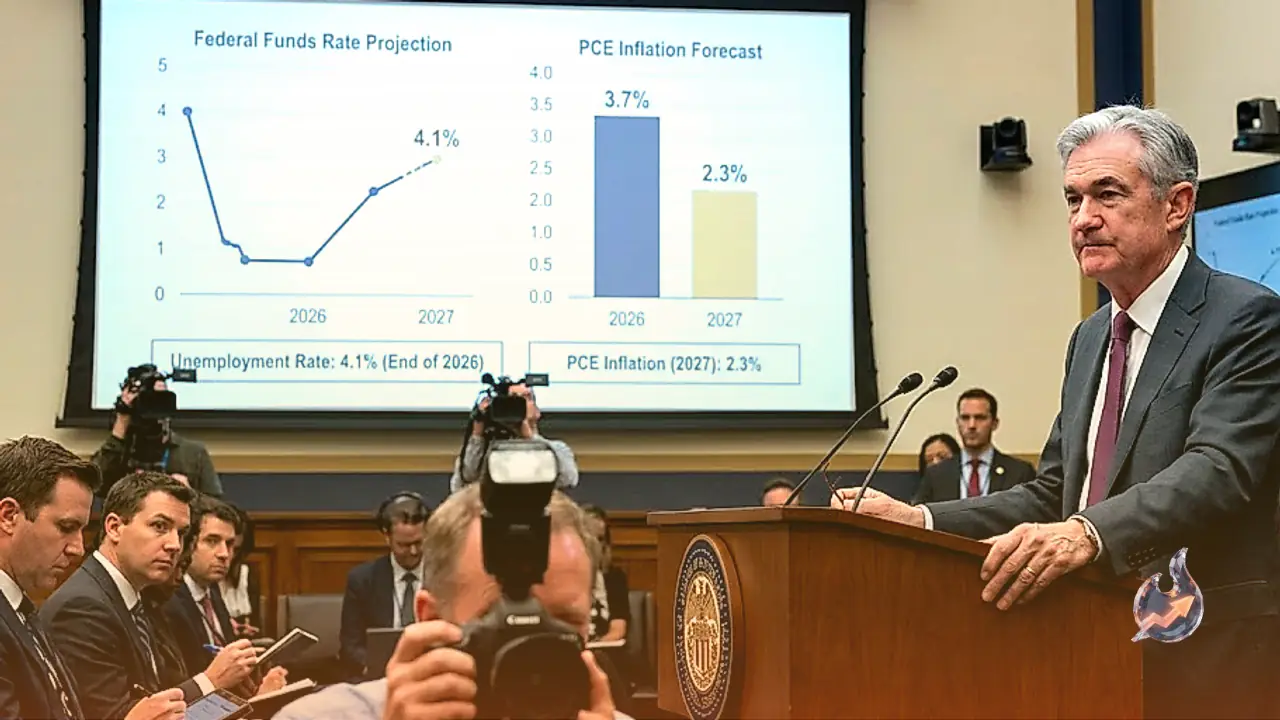















The Federal Reserve’s latest interest-rate decision quickly changed the tone in USD/CAD. The pair climbed 48 pips to its highest level in six weeks, leaving the Canadian dollar, known as the Loonie, at a six-week low.
The move also highlighted a clear policy split. Canada’s rate had not changed in seven meetings, while the US rate had just moved at the Federal Reserve’s decision.
From a narrow range to a sudden burst of activity
For eighteen hours, USD/CAD remained trapped within a band of about 25 pips. During the half hour surrounding the decision, it then traveled twice that distance, replacing the earlier calm with a sudden burst of volatility.
Measured against the level in place before the decision, the gain was 48 pips. Price reached a peak just below 1.4000 and then traded four pips beneath that peak. A separate opening market figure placed the six-week high below 1.3990.
The day’s low was 62 pips lower and was recorded before noon. The market did not return to that low later. The five-minute momentum gauge stood at 72. Every earlier visit to that end of the day’s range had lasted only minutes.
Why the policy gap mattered
Canada’s rate had remained unchanged through seven meetings. The Fed, by contrast, had just adjusted its rate. Currency markets pay close attention to this kind of divergence because a rate change in one country can alter the appeal of holding its money even if the other country leaves its rate untouched.
In this case, no matching Canadian rate move was described. The seven-meeting pause therefore formed the backdrop for the Fed-driven shift in USD/CAD, without establishing what either side will do next.
The Fed’s two main responsibilities
In the United States, the Federal Reserve controls the direction of monetary policy. Its responsibilities center on two mandates: stable prices and full employment. Interest-rate adjustments serve as the main lever for pursuing both.
If price growth becomes too rapid and inflation moves beyond the Fed’s 2% objective, the response can be a rate increase. That makes loans more expensive across the economy. Global investors may then find US holdings more appealing, increasing demand for dollars and supporting the currency.
If inflation moves under 2% or joblessness is excessive, the Fed has room to reduce rates and stimulate borrowing. Easier borrowing conditions can encourage demand for loans, but lower rates may weigh on the Greenback.
The direction of the rate response is central to the currency result. A hike raises the cost of borrowing, while a cut is intended to make borrowing easier. Because exchange rates compare two currencies, the same decision can matter more when the other side is holding rates steady, as Canada did across seven meetings.
How a rate change reaches the currency pair
USD/CAD shows how many Canadian dollars are needed to buy one US dollar. A rise means the USD has strengthened against the CAD, while a decline means the Loonie has strengthened. The Fed hike therefore showed up as both dollar strength and Canadian-dollar weakness in the pair.
The chain starts with borrowing costs. Higher rates make financing more expensive throughout the economy. If global investors shift more funds toward US holdings, demand for dollars can rise and push USD/CAD higher. The 48-pip response around the decision reflected that change in relative appeal.
Because Canada’s rate stayed fixed across seven meetings, the move did not coincide with a matching Canadian rate change. That contrast explains the immediate backdrop, but it does not confirm a future policy path.
Who sets monetary policy
Across a year, the Fed schedules eight meetings devoted to policy. Policymakers on the Federal Open Market Committee (FOMC) review economic conditions at these sessions before deciding the policy stance.
Twelve Fed officials attend the FOMC. The group includes all seven members of the Board of Governors, the Federal Reserve Bank of New York’s president, and four presidents chosen from the other eleven regional Reserve Banks. Those regional seats rotate, and each participating president serves for one year.
Quantitative easing during extreme conditions
When ordinary tools are not enough in an extreme situation, the Fed can turn to quantitative easing (QE). The policy sharply expands credit when the financial system is stuck. It is a non-standard response for crises or periods of extremely low inflation.
QE became the Fed’s preferred response during the Great Financial Crisis of 2008. The mechanism creates additional dollars, which are then deployed to purchase high-grade bonds held by financial institutions. By expanding credit through those purchases, the policy typically weakens the USD.
QE differs from a routine rate adjustment because it works through credit flow and bond purchases. That distinction helps explain its usual currency effect: adding dollars and expanding credit tends to weigh on the USD, while a rate increase can strengthen its appeal.
Quantitative tightening moves in reverse
Quantitative tightening (QT) moves in the opposite direction. In practice, bond purchases from financial institutions come to an end. When a bond in the Fed’s portfolio matures, the returned principal is not used to acquire another bond.
Rather than continuing fresh purchases or recycling maturing principal into the bond market, policy support is allowed to recede. The typical currency consequence of QT is support for the USD, the opposite of QE’s usual effect.
Together, these tools show that the Fed can influence conditions beyond policy-rate changes. Rate adjustments work mainly through borrowing costs and investor appeal, while QE and QT operate through credit flow and bond holdings. Their usual effects on the USD point in opposite directions.
What the price action does and does not establish
The market’s contrast was striking: eighteen hours inside about a 25-pip band, followed by twice that distance in the half hour around the decision. That shows how quickly the Fed action changed trading conditions. Still, the five-minute momentum gauge’s reading of 72 had only lasted minutes during earlier visits that day, so persistence of the latest move is not established.
No next policy outcome has been confirmed. Under the Fed’s framework, inflation relative to 2% and the unemployment rate remain central. The confirmed sequence is a Fed rate increase, seven unchanged Canadian meetings, and a 48-pip rise in USD/CAD to a six-week high.