














Selling pressure has mounted decisively across foreign exchange trading floors, dragging the New Zealand Dollar to its weakest valuation against the US Dollar since the start of July. With second-quarter economic expansion data due imminently, international market participants have trimmed their exposures to the Southern Hemisphere currency. The NZD/USD exchange rate has drifted down to hover barely above 0.5700, failing during the session to mount any sustained push toward 0.5800. The broader retreat marks an extension of a downtrend that originated below 0.6000 in late August, etching a persistent succession of lower peaks across daily trading intervals. This vulnerability comes at a critical juncture, as domestic output figures are expected to show an economy grinding near a standstill under the weight of tight credit conditions.
Quarterly Deceleration and the Statistical Paradox in National Accounts
Statistical authorities in New Zealand are scheduled to unveil second-quarter gross domestic product performance late on Wednesday or early Thursday, depending on regional time zones relative to the international date line. Projections compiled across financial institutions indicate that economic activity expanded by a muted 0.1% over the quarter. This represents a stark deceleration from the 0.8% pace recorded during the first three months of the calendar year. A result in line with these expectations would confirm that consumer belt-tightening and elevated financing hurdles have effectively neutralized business expansion, leaving total production dangerously close to contraction territory.
In a striking statistical contrast, the headline annualized metric is anticipated to accelerate in the opposite direction, moving upward to 2.3% from the previous reading of 1.5%. This apparent divergence is not driven by any sudden resurgence in economic momentum, but rather by the base effects inherent in year-over-year mathematical calculations. The quarters dropping out of the calculation window were considerably weaker than the modest figures replacing them, creating an automatic upward adjustment in the trailing annual sum. Market participants are therefore presented with a dual reality where sequential momentum has largely stalled while year-on-year calculations register an improvement of nearly a full percentage point, requiring thorough analysis to parse true macroeconomic health.
Technical Indicators Signal Entrenched Bearish Control
Price action across daily charts reflects persistent technical weakness that has kept buyers sidelined. The currency cross continues to trade beneath both its 50-day and 200-day Exponential Moving Averages, which have converged tightly around the 0.5850 barrier. Since the early days of September, the exchange rate has been entirely unable to reclaim ground above this critical crossover point, confirming that institutional participants are utilizing short-term rallies to initiate fresh short positions. The structural downward slope remains intact, leaving support levels exposed to further downside exploration.
Momentum oscillators corroborate this heavy market sentiment. The daily Stochastic Relative Strength Index has declined toward the absolute floor of its boundary, touching levels not witnessed since the intense wave of selling in June that drove the pair down just above 0.5600. While deeply suppressed momentum gauges occasionally foreshadow short-term stabilization or technical bounces, the absence of buying volume suggests that market participants remain hesitant to build bullish positions ahead of key data points and ongoing monetary tightening from major central banks.
The Fundamental Mechanism Linking Growth Metrics to Currencies
Gross Domestic Product serves as the foundational gauge of a nation's total economic velocity, measuring the aggregate value of all goods and services generated within its borders over a standard quarterly interval. The clearest analytical comparisons evaluate performance relative to the immediate preceding quarter or against the exact corresponding quarter of the prior year. By contrast, annualized quarterly growth metrics project a single quarter's rate across an entire calendar year. Such annualized projections frequently distort realities during periods of transient external turbulence, as demonstrated during the opening quarter of 2020 when the sudden emergence of the pandemic sent quarterly readings plunging.
Accelerating economic expansion generally underpins currency strength by fostering an environment conducive to export activity and direct foreign capital participation. Conversely, stalling output undermines relative currency appeal. Stronger economic demand typically stimulates consumer spending, which progressively elevates domestic price pressures and inflation. Under such circumstances, central monetary authorities are compelled to raise benchmark borrowing costs to curb runaway consumer prices. An increase in official cash rates enhances deposit returns, enticing foreign portfolio allocations and naturally driving appreciation in the sovereign currency.
Fed Policy Tightening Amplifies Pressures Across Precious Metals
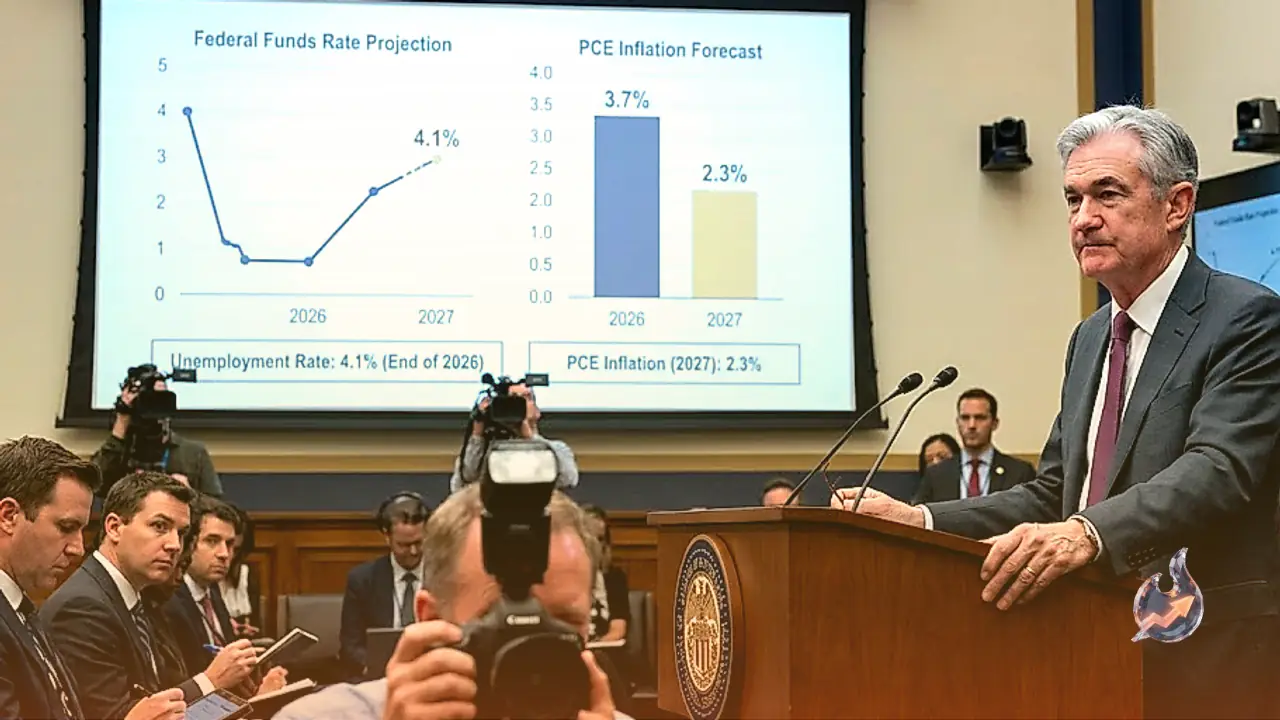
The macroeconomic chain linking economic indicators and policy decisions extends directly into the performance of non-yielding assets, notably bullion. When sovereign debt yields and deposit returns rise in response to central bank actions, the opportunity cost associated with holding non-interest-bearing physical gold expands significantly. Investors often rebalance capital into cash deposits or interest-paying instruments, dampening demand for precious metals. Recent actions from the US Federal Reserve have brought this dynamic to the forefront, as policymakers instituted a 25 basis point hike in benchmark borrowing costs, aligning with baseline market expectations.
Subsequent commentary delivered by Chair Kevin Warsh struck a notably hawkish chord during the post-meeting press conference, stoking expectations that further rate adjustments could occur prior to the close of the calendar year. In response, bullion reversed earlier intraday advances, retreating from peaks above $4,360 toward the $4,250 neighborhood. Live market data places spot gold at $4,303 per ounce, reflecting a 0.70% decline from its prior settlement at $4,333. The metal operates in a broader 52-week band of $3,661 to $5,586, with its 14-day RSI standing at 40 and moving averages showing a death cross pattern as the 50-day EMA at $4,388 sits below the 200-day EMA at $4,416. Crucial chart pivots stand at $4,330, with primary support anchored at $4,246 and secondary cushions at $4,190.
Spillovers Across Asian Currencies and the Shift in Japanese Funding
The ripple effects of a re-energized greenback quickly permeated across broader Asia-Pacific foreign exchange sessions. The Australian Dollar surrendered ground, dipping below the 0.7100 benchmark early in Thursday trade as the US Dollar surged on expectations of sustained American monetary restriction. Concurrently, the USD/JPY currency pair advanced to fresh weekly peaks near 156.00. The pronounced divergence between relentless Federal Reserve firmness and regional monetary policies continues to dictate broad currency valuations.
In Tokyo, financial conditions are navigating an important structural transition. For well over a decade, Japan maintained ultra-loose monetary policy and near-zero borrowing costs, which effectively transformed the Japanese Yen into the premier funding vehicle for global carry trades totaling trillions of dollars. International investors borrowed cheaply in yen to finance higher-yielding ventures across global markets while Japan remained the solitary outlier holding rates down. However, with expectations building that the Bank of Japan may implement policy tightening this week, this long-standing dynamic could undergo substantial shifts, potentially triggering a broader reallocation of global cross-border liquidity.