
















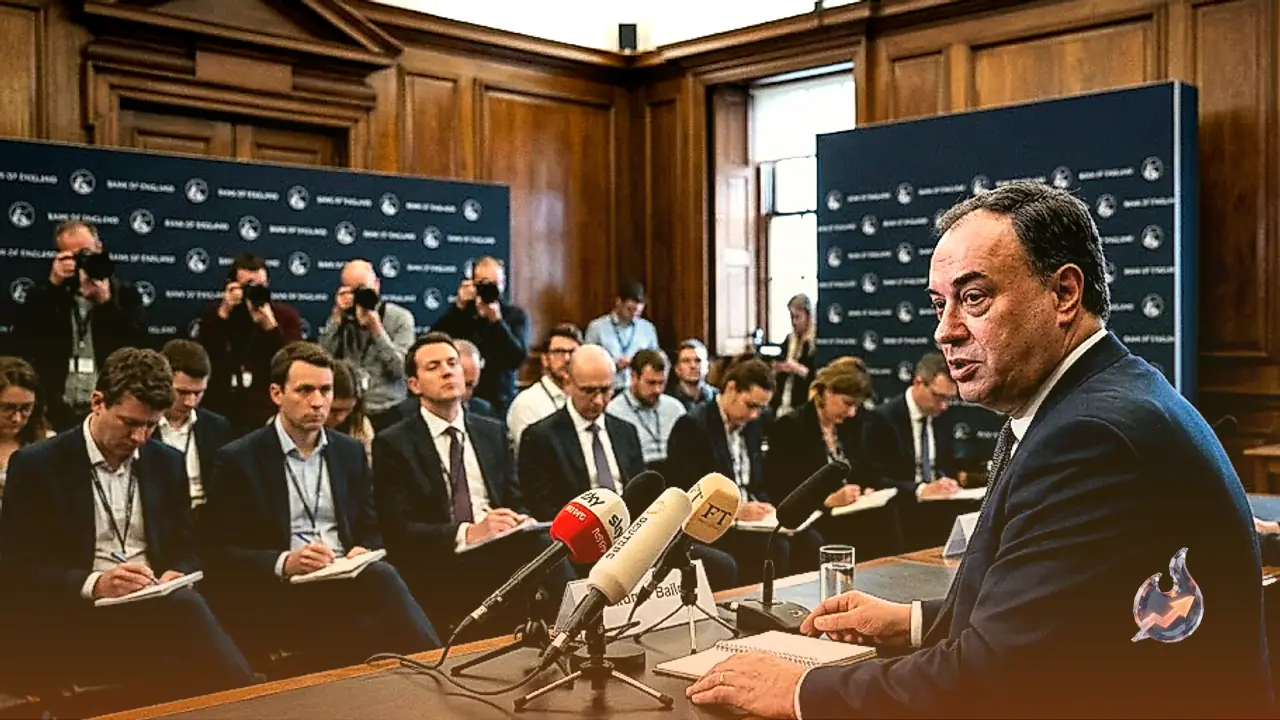

The Monetary Policy Committee of the Bank of England opted to maintain its benchmark Bank Rate at 3.75% following a divided 6-3 vote during its latest policy gathering. While the outcome met broader consensus projections, the tone accompanying the decision revealed a pronounced deterioration in the economic outlook. Central bank officials pointed to compounding external pressures, primarily triggered by elevated energy market prices and the widening Middle East conflict, as substantial catalysts altering the domestic monetary calculus. With cost structures vulnerable to renewed external shocks, market analysts now anticipate that the central bank will be forced to implement a 25 basis point rate increase at its November meeting, pushing borrowing costs to 4.00%.
Energy Disruptions and Intensifying Second-Round Inflation Concerns
The policy message emerging from the rate decision underlined that the distribution of economic risks is tilting heavily toward renewed price pressures. Continued firmness in wholesale energy prices threatens to spill over into broader goods and service production, generating severe second-round inflation effects across the real economy. Policymakers consider these secondary impacts a top priority, as sustained input costs risk unanchoring consumer price expectations. Stefan Koopman noted that the committee's updated communication reflects a rapid darkening of the inflation trajectory, leaving policy authorities with significantly less leeway to tolerate elevated price prints in the coming quarters.
Restricted Room for Tightening and Long-Term Reversal Prospects
Despite the building case for an emergency adjustment in late autumn, underlying domestic macroeconomic fundamentals remain fragile, failing to justify an extended or sustained monetary tightening regime. At its current mark of 3.75%, the Bank Rate already exerts significant restriction on economic activity, operating approximately 50 basis points above the perceived neutral interest rate. Consequently, an incremental 25 basis point move in November is projected to serve as a temporary stabilization measure rather than the start of a protracted rate-hiking campaign. Financial market participants who have priced in a prolonged hiking cycle may be overestimating the resilience of domestic demand. Projections suggest that after an anticipated November lift to 4.00%, the central bank will likely hold rates flat for an extended duration, ultimately necessitating corrective rate reductions across 2027 and 2028 to unwind the excess policy restriction.
Federal Reserve Mandate and Dollar Consolidation
Developments across other core economic hubs have concurrently reshaped global capital movements. The Federal Reserve concluded its own monetary policy review by unanimously raising the Fed Fund Target Range by 25 basis points to a corridor of 3.75% to 4.00%. US central bankers emphasized that the additional policy firming was indispensable to ensure a prompt convergence back to their formal 2% inflation objective. This hawkish decision initially sparked an aggressive greenback rally, driving the US currency to levels unseen since late July. However, during Thursday's Asian trading session, this upward momentum took a pause as global traders consolidated positions ahead of subsequent policy catalysts.
Foreign Exchange Dynamics Across the Pacific
The retreat in broad dollar strength fostered an immediate technical rebound across key international currency pairs. The Australian Dollar gathered renewed buying momentum in Asian trading on Thursday, successfully reclaiming the 0.7100 threshold. Market participants attributed the currency's positive performance to escalating bets on an upcoming interest rate hike by the Reserve Bank of Australia, combined with diplomatic progress surrounding US-Iran discussions that offered temporary relief to broader market sentiment and risk-sensitive assets.
Simultaneously, the USD/JPY cross pulled back from an early drop below the 156.00 mark during Asian market hours, attempting to halt a three-day winning streak that had driven the dollar to near two-week highs against the Japanese currency. The greenback’s stabilization following a post-Fed rally to seven-week peaks, alongside expanding expectations that the Bank of Japan will proceed with its policy normalization timetable, provided structural support to the Japanese Yen. These opposing forces capped the pair's upward scope, with investor attention gravitating toward the Bank of Japan’s impending policy conclusion scheduled for Friday.
Transformation of Japan's Global Carry Trade Advantage
For more than a decade, Japan's framework of ultra-low domestic borrowing costs functioned as an essential funding mechanism for international financial markets. Ultra-accommodative conditions made the Japanese Yen an unprecedented vehicle for cross-border investments, helping deploy trillions of dollars worldwide through the carry trade. While other developed nations aggressively tightened monetary conditions to combat post-pandemic inflation, Japan stood out as a persistent exception. With market participants actively anticipating another policy tightening maneuver from the Bank of Japan this week, the decade-long era of ultra-cheap yen-denominated funding appears to be transitioning into an unpredictable and restrictive phase.
Gold Surge and Energy Price Retracement
Commodity markets reacted dynamically to shifting sovereign yield trajectories and foreign exchange repositioning. Gold prices advanced decisively on Thursday, establishing fresh weekly peaks around the $4,480 per troy ounce zone. The pronounced recovery in bullion snapped a consecutive three-day slide, drawing direct impetus from the broad-based pullback in the US Dollar and ongoing downward price adjustments in crude oil contracts. The confluence of geopolitical uncertainty and elevated bond yields continues to steer institutional capital toward safe-haven physical assets.